

Blogs
NB Latex Market 2026-2032: Why 7.45% CAGR and the $215M 2025 Milestone Redefine Growth Dynamics
By PW Consulting, 2026-09-21
Navigating the NB Latex Market: Strategic Trends and Commercial Opportunities Through 2032
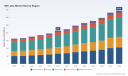
The NB Latex Market has matured from a commodity-driven segment into a strategically differentiated landscape where performance specifications, supply chain resilience, and regulatory compliance increasingly determine competitive advantage. Measured in 2025 at approximately USD 215.0 million, the market expanded at a compound annual rate of 7.45% between 2020 and 2025, and forward projections point to sustained momentum through the end of the decade. By 2032, total market size is expected to reach USD 344.8 million, reflecting a trajectory that rewards players capable of aligning product quality, geographic exposure, and operational efficiency with evolving demand patterns.
PW Consulting Health Care Research Center
This growth trajectory is not distributed uniformly. Demand pull comes from multiple end-use channels, while supply-side dynamics remain anchored in a concentrated group of processors and exporters with significant regional footprints. The intersection of tighter environmental regulation, shifting raw material economics, and product specialization is reshaping how value is captured across the chain. For executives and investors, the central question is no longer whether the market will grow, but where differentiation will emerge and how quickly operational models can adapt.
Market Context: Size, Trajectory, and Structural Pressures
A Market Defined by Steady Expansion and Fragmented Value Capture
The overall market has progressed from USD 163.15 million in 2020 to USD 215.0 million in 2025, with the pace of expansion accelerating in recent years as downstream applications broaden and higher-grade latex specifications gain acceptance. The forecast window to 2032 implies continued compounding, though the path will likely be uneven as raw material volatility, regulatory deadlines, and regional demand cycles introduce periodic adjustments. A top-line CAGR of 7.45% signals healthy underlying demand, but it also raises the bar for operational execution, since margin capture increasingly depends on grade consistency, certification readiness, and logistics optimization rather than volume alone.
The value chain remains moderately concentrated. The top three participants account for roughly 23.5% of market revenue, and the top five collectively represent about 28.7%. This structure suggests room for competitive maneuvering, particularly for mid-tier processors that can secure reliable feedstock, differentiate on specialty grades, or embed themselves in customer-specific supply programs. At the same time, the presence of larger, vertically integrated operators indicates that scale advantages in processing capacity, quality control, and export logistics will continue to matter.
Worldwide Latex Binders Market
Key Challenges and Inflection Points
Several structural pressures are redefining the operating environment. First, compliance costs and traceability requirements are rising. The European Union Deforestation Regulation requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance. Enforcement timelines have been adjusted, with large and medium operators facing a December 2026 deadline and micro and small operators a June 2027 deadline following changes made in December 2025. This creates a near-term implementation squeeze: companies must build or verify plantation-level traceability, document chain-of-custody processes, and stand ready for customer and regulator scrutiny without derailing existing export flows.
Second, raw material economics are under continuous renegotiation. Price signals in related commodity markets can influence input cost expectations and plantation economics. For example, palm oil prices fell to 4,554 MYR/T on June 5, 2026, down 1.02% from the previous day, while rising 0.60% over the past month and 16.26% compared to the same time last year. Such movements illustrate how agricultural commodity markets can oscillate within short windows, affecting cost planning and hedging strategies for processors that operate around interlinked feedstock ecosystems. In a related policy move, Indonesia raised the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, directly increasing production costs for palm oil producers. Although this measure targets palm oil, it reflects a broader pattern of export-duty adjustments in producing countries that can indirectly shape cost structures, trade flows, and regional competitiveness for processors handling multiple agricultural streams.
Third, demand-side expectations are shifting from volume to performance. Buyers increasingly seek latex grades that meet tighter technical specifications, consistent viscosity and purity profiles, and certifications aligned with downstream manufacturing requirements. This creates a divide between suppliers that can reliably deliver standardized, certified products and those that remain dependent on more variable commodity streams. The market is therefore approaching an inflection point where quality assurance and documentation capabilities are becoming as commercially significant as capacity.
Key Drivers Shaping the NB Latex Market
Technical Innovation and Grade Specialization
Innovation in latex processing is increasingly oriented around consistency, contamination control, and specification alignment. For automotive and industrial users, tighter tolerances and dependable lot-to-lot performance reduce downstream processing risk and support broader use in higher-value applications. Suppliers with strong process control, filtration and stabilization capabilities, and quality-certified grades are better positioned to serve customers that require repeatable input characteristics. In practical terms, innovation here is less about radical product reinvention and more about process refinement, analytical rigor, and the ability to package reliability as a commercial differentiator.
This trend benefits processors that can demonstrate controlled parameters and certified output. It also raises the importance of technical service: customers are more likely to commit to suppliers who can support specification matching, troubleshooting, and supply continuity. As a result, the competitive edge is shifting toward organizations that combine operational discipline with application-aware customer engagement.
Policy and Regulatory Environment
Regulatory developments are emerging as a structural driver rather than a peripheral compliance issue. The EU Deforestation Regulation is a prominent example: it requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance. The enforcement timeline has been postponed to 30 December 2026 for large and medium operators and to 30 June 2027 for micro and small operators following December 2025 changes. While the postponement provides additional preparation time, the direction of travel is clear: traceability and geolocation documentation are becoming prerequisites for continued access to European channels.
For exporters and processors, the practical implication is that compliance readiness will increasingly influence market access, buyer selection, and contract negotiation dynamics. Companies that invest early in mapping plantation sources, strengthening documentation, and aligning internal processes with geolocation requirements will be better placed to maintain relationships with customers that prioritize regulatory assurance. Those that delay could face higher transaction costs, reduced optionality, or exclusion from certain procurement programs.
Demand-Side Evolution Across End-Use Segments
Demand is broadening beyond traditional channels, and the composition of growth is changing. Automotive applications remain a significant pull, supported by tire and component requirements that favor reliable natural rubber latex inputs. Construction and building materials, consumer goods and personal care, industrial products, and other segments each contribute to aggregate demand in different ways, with varying sensitivity to price, specification, and certification. What matters strategically is that downstream industries are not moving in lockstep. Some channels prioritize cost efficiency, while others place greater weight on performance consistency or compliance documentation.
This segmentation of demand means suppliers need flexible commercial models. A single product strategy is less effective when customers in different verticals evaluate trade-offs differently. Processors that can offer multiple grade options, maintain clear segregation of volumes by specification, and align supply with customer-specific requirements are more likely to retain share as demand patterns shift. The ability to anticipate which segments will expand faster, and to align capacity and certifications accordingly, will be a meaningful source of advantage.
Supply Chain and Cost Structure Dynamics
Cost structures in the NB Latex Market are shaped by feedstock availability, processing efficiency, logistics, and the broader policy environment in producing regions. Price signals from commodity markets can influence planning horizons and risk management decisions. The recent movement in palm oil prices illustrates the kind of volatility that processors may observe in adjacent agricultural markets, with short-term declines coexisting alongside stronger year-on-year comparisons. On the policy side, Indonesia raised the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, directly increasing production costs for palm oil producers. Such measures matter because they reflect a recurring theme: producing countries periodically adjust export duties and related fiscal instruments, which can alter cost competitiveness and trade routing over time.
At the same time, supply tightness in major producing countries continues to influence pricing expectations. The World Bank projected Technically Specified Rubber 20 natural rubber prices to increase approximately 7.3% in 2026 to around USD 1.90 per kilogram, supported by steady automotive-sector demand growth and ongoing supply tightness across major producing countries. This outlook underscores that feedstock economics will remain an important variable for latex processors, particularly where natural rubber is a central input. Companies that can manage procurement risk, secure dependable supply, and optimize processing yields will be better equipped to navigate price fluctuations without sacrificing margin stability.
Competitive Landscape: Positioning, Differentiation, and Evolution
Core Players and Strategic Positioning
The competitive set is anchored by processors and exporters with significant capacity and regional reach, many based in Thailand and neighboring Southeast Asian markets, alongside integrated traders and producers in broader Asian supply chains. Several companies stand out for the way they combine capacity, grade focus, and supply chain positioning.
Latex Powder Market
- Sri Trang Agro-Industry Public Company Limited operates as a leading producer and exporter of natural rubber latex concentrate, with global processing capacity exceeding 1.5 million tonnes per year and about 10% share of global natural rubber consumption. Its scale and market participation give it a strong base for volume reliability and broad customer coverage.
- Von Bundit Co., Ltd. is a major processor and exporter of natural rubber latex with production capacity of approximately 2 million tonnes per annum and emphasis on quality-certified grades. This positions the company around specification reliability and certified output, which aligns with buyers seeking consistent input quality.
- Halcyon Agri Corporation Limited is an integrated producer and processor of natural rubber latex serving tire, glove, and industrial applications with vertical supply chain control. Vertical integration can reduce dependency on external procurement channels and support more controlled feedstock and processing flows.
- Thai Rubber Latex Group Public Company Limited supplies concentrated and creamed natural rubber latex with focus on export volumes to Malaysia, China, and other markets. Its export-oriented profile highlights the importance of logistics, destination-market relationships, and trade routing.
- Southland Rubber Co., Ltd. processes natural rubber latex and solid rubber products with capabilities in specialty grades for healthcare and industrial uses. Specialty-grade capability is a notable differentiator in segments where regulated or performance-sensitive applications matter.
- Thai Hua Rubber Public Company Limited is a major player in concentrated natural rubber latex production and export from Thai plantations. Its positioning reflects the continuing importance of Thailand as a processing and export hub.
- Vietnam Rubber Group is a state-linked producer and exporter of natural rubber latex concentrate with significant share in Southeast Asian supply. Its role illustrates how national-level institutions can influence regional supply dynamics and export availability.
- Sinochem International Corporation is an integrated trader and processor supplying natural rubber latex to global markets. Trade and processing integration can support broad market reach and flexible supply arrangements.
- Num Rubber & Latex Co., Ltd. is an active manufacturer of natural rubber latex products and concentrates for medical and industrial applications. Its focus on medical and industrial segments points to the value of application-specific product development and certification readiness.
- Apcotex Industries Limited is a supplier of natural rubber latex for adhesive, coating, and industrial applications. This specialization highlights demand from industrial formulation uses where latex properties influence end-product performance.
Differentiation Themes Among Leading Players
Across this group, several differentiation themes recur. Scale and processing capacity provide volume reliability and the ability to serve large, multi-site customers. Quality-certified grades and specialty offerings support access to more demanding applications, where specification adherence and documentation are critical. Vertical supply chain control and integration can improve feedstock security and reduce exposure to intermediate market disruptions. Export orientation and destination-market relationships shape commercial reach, especially where logistics, customs coordination, and customer proximity influence service levels. Application-specific focus, whether in healthcare, industrial formulation, tire-related uses, or consumer-adjacent products, allows suppliers to build deeper relationships and more tailored value propositions.
The strategic implication is that no single advantage is sufficient on its own. Capacity without quality control limits access to premium channels. Quality and certification without reliable supply can undermine customer confidence. Export relationships without compliance readiness become riskier as regulatory expectations rise. The strongest positions tend to combine several of these elements in a coherent operating model.
Market Structure Evolution: Consolidation, Diversification, and New Entry
The market is likely to evolve through a combination of consolidation among scaled processors, diversification into higher-value grades and applications, and selective new entry where niche positioning or regional advantages are strong. Moderate concentration leaves space for competitive shifts, but it also encourages larger players to deepen customer commitments, strengthen traceability, and invest in process consistency. Mid-tier participants may pursue specialization, regional partnerships, or certification-driven differentiation to expand their addressable market without competing purely on volume.
New entry is most plausible where companies can demonstrate a clear value proposition: reliable traceability, specialty-grade capability, cost-efficient processing, or access to underserved destination markets. In contrast, entry that relies only on commodity positioning is harder to sustain as buyers increasingly weigh specification reliability and compliance assurance alongside price. Over time, the landscape may become more layered, with premium, certified, and application-specific segments becoming more distinct from standard commodity-grade channels.
Outlook: Three Strategic Trends to 2032
Trend 1: Compliance and Traceability as Commercial Gatekeepers
Traceability and geolocation readiness will increasingly function as commercial gatekeepers for access to regulated markets. The EU Deforestation Regulation requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance, and the adjusted enforcement schedule still places large and medium operators under a December 2026 deadline and smaller operators under a June 2027 deadline. This timeline creates a practical window for preparation, but it also raises the likelihood that compliance maturity will influence buyer decisions and contract eligibility.
The commercial opportunity lies in turning compliance into a differentiator. Suppliers that can present verifiable plantation-level data, robust documentation, and repeatable audit readiness may find it easier to enter or retain relationships with customers that require regulatory assurance. The risk is that companies with weak traceability infrastructure face growing friction, higher transaction costs, or narrowing market access, especially in channels where buyers are especially sensitive to regulatory exposure.
Trend 2: Grade Specialization and Specification-Driven Demand
Demand is expected to place greater weight on specification consistency, certified grades, and application-aligned product attributes. Automotive and industrial channels, in particular, benefit from latex inputs that support stable downstream processing and predictable performance. This favors processors that can maintain tight control over quality parameters and deliver certified output with dependable lot consistency.
For commercial strategy, this trend suggests a shift toward value-based positioning rather than price-only competition. Companies that can match grades to customer requirements, provide technical support, and ensure supply continuity may command stronger relationships and better margin protection. The uncertainty is that specification demands may diverge across segments, requiring suppliers to manage a broader set of product configurations without losing operational efficiency.
Trend 3: Supply-Side Volatility and the Need for Procurement Resilience
Feedstock economics and policy adjustments will continue to shape cost structures and supply planning. With natural rubber prices projected to increase approximately 7.3% in 2026 to around USD 1.90 per kilogram, supported by steady automotive-sector demand growth and ongoing supply tightness across major producing countries, processors should expect continued pressure on input economics. At the same time, policy actions such as Indonesia raising the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, and short-term commodity price movements like palm oil falling to 4,554 MYR/T on June 5, 2026, illustrate how quickly cost expectations can shift in adjacent agricultural markets.
The strategic response is to build procurement resilience: diversified sourcing where feasible, stronger supplier relationships, improved yield and process efficiency, and disciplined risk management. The opportunity is to reduce vulnerability to price spikes and supply interruptions while maintaining competitive pricing for customers. The risk is that firms with limited flexibility may face margin compression or supply uncertainty when markets tighten or policy changes alter cost dynamics.
Actionable Recommendations for Decision-Makers
For Manufacturers and Processors
Invest early in traceability and documentation infrastructure, especially if European market access is part of the commercial plan. Plantation-level geolocation readiness, chain-of-custody records, and auditable process controls will become more valuable as deadlines approach and buyer expectations firm up. At the same time, review grade architecture and quality systems to ensure the product mix supports specification-driven demand. Where possible, strengthen process consistency and certification readiness so the business can serve higher-value applications without compromising reliability.
For Investors
Look beyond aggregate market size and focus on the structural attributes that determine durable value capture. Scale, vertical integration, certification capability, specialty-grade positioning, and compliance readiness each influence competitive resilience in different ways. Evaluate whether target companies have credible pathways to maintain supply security, meet rising traceability expectations, and serve demand channels that are expanding faster than the average. Pay attention to regional exposure and policy risk, since export-duty changes and commodity price volatility can affect cost structures and trade routing over time.
For Procurement and Supply Chain Leaders
Treat latex sourcing as a multi-factor decision rather than a price-only exercise. Specification consistency, certification status, traceability readiness, and supply continuity should be weighted alongside cost, particularly where downstream manufacturing risk or regulatory exposure is significant. Diversify sourcing where feasible, clarify documentation requirements with suppliers, and establish expectations for geolocation and compliance data if EU-market-bound products are in scope. Building these expectations into procurement criteria early can reduce disruption later and improve negotiating leverage.
The NB Latex Market is entering a phase in which growth is necessary but not sufficient. The companies and investors that fare best will be those that treat compliance readiness, grade specialization, and supply resilience as core strategic capabilities rather than operational afterthoughts. Detailed segmentation data, company-level benchmarks, and scenario-based guidance can help convert these strategic themes into specific investment, sourcing, and product decisions. Readers seeking a more granular view of regional splits, application dynamics, type-level comparisons, and competitive positioning can access the full PW Consulting report for detailed figures and customized recommendations tailored to their commercial objectives.
For detailed analysis of this topic, please visit the official page: NB Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Algae Products Market Surpasses $15B: 8.2% CAGR Trajectory and 3 Strategic Shifts
By PW Consulting, 2026-09-21
Strategic Horizons: Navigating Growth and Complexity in the Algae Products Market
1. Market Trajectory and Core Pressures
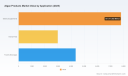
The global algae products market has entered a phase of accelerated expansion, driven by converging forces across nutrition, industrial sustainability, and biotechnological innovation. Valued at approximately $9,400 million in 2020, the sector has more than doubled in relative terms, reaching an estimated $15,151 million by 2025. Current projections indicate a steady growth trajectory through 2032, with a compound annual growth rate of 8.2 percent, positioning the market to approach $26.3 billion by the end of the forecast period. This expansion reflects a structural shift rather than a cyclical upturn, as algae-derived ingredients move from niche applications into mainstream dietary supplements, functional foods, animal nutrition, and industrial raw materials.
Worldwide Algal Biofuel Market
Despite the favorable trajectory, the industry stands at a critical juncture where scaling ambitions intersect with operational and regulatory realities. Three interlocking challenges define the current landscape. First, production scalability remains uneven across cultivation methods, with open-pond systems facing climate dependency and contamination risks, while closed photobioreactor and heterotrophic fermentation platforms demand significant capital investment and energy optimization. Second, regulatory scrutiny has intensified in key export markets, particularly around contaminant thresholds, strain-specific safety assessments, and novel-food categorization, raising compliance costs and lengthening time-to-market for new ingredients. Third, the supply chain for high-value fractions such as omega-3 oils, phycocyanin, and specialty proteins continues to experience bottlenecks in downstream processing, drying, and stabilization, which compress margins and limit format flexibility. These pressures are not insurmountable, but they require coordinated investment in process engineering, quality systems, and regional regulatory strategy.
2. Force Multipliers: What Is Driving the Market Forward
Technological Innovation and Strain-Level Breakthroughs
Advancements in cultivation architecture, strain selection, and downstream fractionation are reshaping the economics of algae production. Industry participants are increasingly pairing controlled-environment systems with real-time monitoring, automated feeding, and precision harvesting to improve yield consistency and reduce water and energy intensity. The integration of digital control systems into cultivation facilities has enabled tighter management of growth conditions, which is particularly valuable for high-potency extracts where potency, purity, and batch repeatability command premium pricing. Parallel progress in heterotrophic fermentation and metabolic engineering is expanding the range of commercially viable strains, allowing producers to decouple output from seasonal sunlight and weather variability. These developments are lowering the cost curve for specialized molecules while creating new format options for end users, from stabilized powders to concentrated oils and colorants.
Regulatory Evolution as a Market Catalyst
Regulatory dynamics in major markets are simultaneously tightening and enabling. In 2025, additional chlorella and spirulina strains received Generally Recognized as Safe status in the United States, broadening the formulation toolkit for supplement and food manufacturers. Around the same period, the European Food Safety Authority granted novel-food approvals for algae-derived omega-3 oils and phycocyanin colorants, opening doors for ingredient diversification in European markets. At the same time, both EFSA and the United States Pharmacopeia tightened contaminant thresholds for algae-based ingredients, elevating quality assurance expectations across the value chain. The net effect is a market that rewards disciplined producers with robust analytical capabilities, traceable sourcing, and documented process controls. Regulatory clarity, where it emerges, reduces uncertainty for downstream buyers and accelerates ingredient adoption, while stricter thresholds raise the competitive bar for entrants lacking validated quality infrastructure.
Demand-Side Shifts and Portfolio Reconfiguration
Consumer and corporate behavior is reordering ingredient preferences across multiple categories. Health-conscious consumers are increasingly seeking plant-based, ocean-friendly alternatives to fish-derived omega-3s, a trend that is expanding the addressable market for algal DHA and EPA oils in supplements, functional foods, and maternal nutrition. Beyond personal nutrition, manufacturers in food and beverage are exploring algae-derived proteins, colorants, and texturizing agents to support clean-label and sustainability claims. In animal nutrition, the push for alternative protein and lipid sources in aquaculture and livestock feed is creating incremental demand for algae-based meals and oils, particularly where feed conversion efficiency and disease resistance are priorities. These demand signals are not uniform, but they are broad enough to support diversified product strategies and reduce reliance on any single application vertical.
Supply Chain and Cost Structure Realignment
Cost competitiveness in the algae sector is increasingly determined by downstream efficiency and geographic positioning. Energy consumption, water management, harvesting yield, and drying technology are the primary levers that separate margin-resilient operations from those exposed to commodity volatility. Recent moves to localize cultivation and processing in regions with favorable climate, renewable energy access, and proximity to end markets are helping participants manage freight costs and reduce lead times. At the same time, partnerships between ingredient specialists and technology or agricultural partners are accelerating the commercialization of novel molecules, particularly astaxanthin and high-potency omega-3 fractions. Together, these shifts are turning cost structure from a static constraint into a dynamic design variable, where process choice, location, and collaboration model directly influence market positioning.
3. Competitive Dynamics and Strategic Positioning
The competitive landscape is characterized by a mix of established life-science and ingredients multinationals, specialized algae producers, and emerging technology-driven entrants. Market concentration is significant, with the top three players accounting for approximately 68 percent of revenue and the top five capturing roughly 82 percent, underscoring the advantage of scale, regulatory experience, and integrated supply chains. Yet the ecosystem also includes highly specialized firms that compete on potency, strain uniqueness, geographic sourcing, or application expertise, creating a layered market where leadership is defined as much by differentiation as by volume.
A review of recent corporate activity illustrates how participants are building durable advantage. In mid-2025, a leading algae-based omega-3 and specialty ingredients supplier secured regulatory approval in China for its algae-based omega-3 solutions, extending its commercial footprint into a high-growth market and strengthening its position in nutraceutical and food applications. Shortly thereafter, the same company partnered with an agricultural systems specialist to develop and commercialize natural astaxanthin derived from heterotrophic microalgae, signaling a deliberate expansion into high-value colorant and nutraceutical molecules through collaborative commercialization. In early 2025, a major spirulina producer inaugurated a new cultivation facility equipped with AI-enabled process control, SCADA monitoring, robotics, and zero-discharge systems, demonstrating how operational automation and environmental controls are being embedded into capacity expansion. In the second half of 2025, a prominent life-science and nutrition player launched an ultra-potent algal DHA oil formulation delivering substantially higher DHA and meaningful EPA levels per gram, targeting infant nutrition and premium supplement formats where concentration and dosage efficiency matter. Earlier, in late 2024, a collaborative product launch introduced microalgae-derived cooking oils produced via fermentation from sugarcane sugars, illustrating how alternative feedstock pathways and fermentation platforms are entering the consumer-facing food ingredient space.
Strategic Archetypes in the Market
These activities reveal several distinct strategic archetypes. One is the integrated multinational that leverages regulatory expertise, global distribution, and application support to dominate high-volume categories such as omega-3 oils and nutrition ingredients. Another is the specialist producer that competes on geographic origin, strain heritage, and purity narratives, often building loyalty through quality certification and category-specific formulation knowledge. A third is the technology-forward entrant that uses photobioreactors, fermentation, or advanced downstream processing to access molecules with superior potency, consistency, or cost profiles. Each archetype carries trade-offs: scale and integration support pricing power and market access, while specialization and technology intensity support margin resilience and differentiation but demand disciplined capital allocation and execution.
Evolution of the Competitive Map
Looking ahead, the market is likely to experience both consolidation and fragmentation simultaneously. Larger players will continue to pursue portfolio breadth, regulatory wins, and regional capacity to secure supply reliability for demanding buyers. At the same time, targeted partnerships and licensing arrangements will allow smaller or more specialized firms to commercialize novel molecules without bearing the full burden of standalone scale-up. New entrants with strong fermentation, strain engineering, or process automation capabilities may capture specific formulation niches, particularly where potency, sustainability, or clean-label positioning create meaningful price premiums. The net result is a market in which competitive advantage will increasingly depend on the ability to combine quality assurance, process efficiency, regulatory fluency, and application-specific value propositions rather than on volume alone.
PW Consulting Health Care Research Center
4. Forward Outlook: Trends Shaping the Next 3–5 Years
Three trends are likely to define the market’s evolution over the next several years. The first is the continued migration of algae-derived ingredients from specialty niches into mainstream nutrition and food formats. As regulatory approvals broaden and formulation know-how matures, algae-based omega-3s, proteins, colorants, and functional extracts will appear in more conventional product architectures, supported by consumer preference for plant-based and traceable inputs. The commercial opportunity here lies in format innovation and application engineering: products that deliver dosing convenience, sensory compatibility, and stability will gain shelf preference and retail traction.
The second trend is the growing importance of process intensity and digital control as margin determinants. Facilities that integrate automated cultivation management, precise harvesting, and energy-efficient drying will be better positioned to meet rising quality expectations while managing unit costs. Heterotrophic fermentation and hybrid cultivation models will expand where feedstock availability and process economics align, enabling more predictable output and reducing exposure to climate variability. For commercial teams, the implication is clear: sourcing decisions and partnership strategies should account for process transparency, quality documentation, and scalability pathways, not just current price points.
The third trend is regulatory normalization paired with higher compliance baselines. As more strains and ingredient categories secure approvals and contaminant thresholds become more stringent, the market will reward producers that demonstrate analytical rigor, batch traceability, and consistent documentation. This dynamic will raise barriers for low-cost, low-control operators while creating a more stable environment for established suppliers and well-capitalized newcomers. The associated risk is that compliance costs and approval timelines may compress short-term capacity additions, and that divergence in regional standards could complicate global supply strategies if not managed proactively.
5. Strategic Implications for Decision Makers
For manufacturers and ingredient developers, the priority is to align product roadmaps with where regulatory clarity, demand momentum, and process advantage intersect. This means prioritizing molecules and formats with clear adoption pathways, investing in quality systems and analytical capabilities that satisfy tightening contaminant thresholds, and selecting cultivation or fermentation models that match target margin profiles and volume requirements. Companies should also evaluate partnerships that can accelerate commercialization of high-value fractions, particularly where collaborative models reduce capital exposure while securing supply reliability.
For investors, the key is to distinguish durable advantage from short-term momentum. Favor platforms that combine regulatory track records, process automation, and defensible strain or formulation IP with evidence of scalable unit economics. Evaluate exposure to regional regulatory timelines and contaminant compliance costs, and assess whether a company’s competitive positioning depends on volume, potency, or differentiation. Diversification across applications can reduce concentration risk, but only when each vertical has a credible cost and quality story.
For procurement and formulation teams, the emphasis should be on supply resilience and specification integrity. Build multi-source strategies where feasible, prioritize suppliers with documented quality controls and robust traceability, and validate performance under real formulation conditions rather than relying on potency claims alone. As regulatory expectations rise and demand expands across food, supplement, and feed applications, procurement decisions that embed quality, compliance, and scalability considerations will reduce downstream disruption and support faster time-to-market.
As the market continues to scale, the difference between marginal participation and strategic advantage will increasingly come down to the precision of market intelligence. Detailed segmentation data, regional regulatory tracking, pricing and margin dynamics, and company-level capability assessments are essential inputs for capital allocation, partnership decisions, and formulation planning. Readers seeking deeper segmentation detail, regional demand patterns, and customized strategic recommendations can access the full research report for granular data and tailored guidance.
Microalgae Market
For detailed analysis of this topic, please visit the official page: Algae Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High Precision Planetary Gear Reducers Market: How Asia Pacific’s 1772M Demand Reshapes Growth
By PW Consulting, 2026-09-21
High Precision Planetary Gear Reducers: Strategic Trends and Commercial Opportunities in a Maturing Market
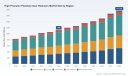
The high precision planetary gear reducer market has entered a phase of disciplined expansion, transitioning from a niche component supplier ecosystem to a critical enabler of next-generation motion control. Valued at approximately $1,140 million in 2025, the market has sustained a compound annual growth rate of 6.5% over the 2026–2032 horizon, with forward projections pointing toward $1,771 million by 2032. This trajectory reflects a fundamental shift in how industrial systems are engineered: precision gearing is no longer a passive power transmission element but an active determinant of throughput, energy efficiency, and operational reliability. The market’s evolution is shaped by tightening technical standards, accelerating automation adoption, and a competitive landscape where regional manufacturing footprints and application-specific engineering increasingly dictate commercial advantage.
For executives and investors, the opportunity lies not in capturing volume at any cost, but in aligning product architectures with the demand curves that will define the next decade. The following analysis maps the structural drivers, competitive dynamics, and actionable positioning strategies that will determine which players capture sustainable margin expansion and market relevance.
Market现状与核心挑战
The market’s current size and forecast profile reveal a sector that has survived the volatility of the early 2020s and is now consolidating around predictable, application-driven demand. Growth is no longer propelled by broad industrial recovery alone but by specific technology adoption cycles where precision gearing serves as a bottleneck or enabler. Three structural challenges define the current inflection point.
Precision Verification and Thermal Stability Requirements
Transmission performance is increasingly evaluated under dynamic operating conditions rather than static laboratory benchmarks. Updated international transmission precision guidelines now incorporate more stringent dynamic testing requirements under thermal equilibrium, raising the bar for validation protocols and forcing manufacturers to redesign testing infrastructure and quality assurance workflows. This shift compresses development cycles for new product lines, increases certification costs, and rewards suppliers who can demonstrate repeatable performance under sustained thermal loads. Companies that rely on legacy verification methods face higher rejection rates, longer customization lead times, and diminished credibility in applications where micro-backlash variations directly translate into positioning errors.
Automation Adoption as a Volume Amplifier
Global industrial robot installations surpassed 590,000 units in 2023, with over 62% of those installations incorporating high precision planetary gear reducers for torque control and precision motion. Simultaneously, the adoption of servo-based automation systems expanded by 13.4% in 2024, reflecting a broader structural preference for closed-loop motion control in both discrete manufacturing and process equipment. This demand surge is not uniform across sectors; it concentrates where cycle time reduction, repeatability, and footprint constraints justify the premium for precision gearing. The challenge for suppliers is to scale production without diluting engineering responsiveness, as standardization and application support become equally valuable as raw output capacity.
Geopolitical and Regional Manufacturing Realignment
Machine tool exports exceeded $10.7 billion in 2023, underscoring the continued strength of precision manufacturing exports in major industrial economies. Yet the same export momentum coincides with growing localization pressure in end markets, where lead time expectations, supply chain resilience, and total cost of ownership calculations are pushing buyers toward regional assembly and faster catalog fulfillment. Suppliers that depend on centralized production and long freight routes are encountering longer quotation-to-delivery windows, currency exposure, and reduced agility in responding to regional specification variations. The market is gradually rewarding localized capacity and modular product platforms that can be configured close to the point of use.
关键驱动因素分析
The market’s growth trajectory is being pulled by a small set of structural forces that interact with each other faster than historical forecasting models anticipated. Understanding these drivers is essential for prioritizing R&D investment, capacity strategy, and commercial positioning.
PW Consulting Automotive & Machinery Research Center
Technical Innovation and Materials Engineering
Precision gearing performance is increasingly determined by material selection, heat treatment consistency, and gear geometry optimization rather than by incremental scale gains. Manufacturers are moving toward carburized alloy steels and multi-planetary architectures that distribute load more evenly across tooth engagement surfaces, extending fatigue life and reducing torque ripple under variable loading. These design choices directly address the thermal stability requirements now embedded in updated precision guidelines, enabling gearboxes to maintain backlash characteristics across longer duty cycles. Innovation is also extending into lubrication management, sealing integrity, and housing stiffness, where marginal gains compound into measurable improvements in positioning accuracy and maintenance intervals. For suppliers, the commercial implication is clear: technical differentiation is shifting from catalog specifications to verifiable performance under real operating conditions, and the winners will be those who can translate materials engineering into documented reliability advantages.
Policy and Standardization Momentum
Standardization is no longer a passive compliance exercise; it is actively shaping purchasing criteria and supplier qualification. The updated transmission precision framework has elevated dynamic thermal testing from an advisory practice to a market expectation, which in turn creates a barrier for suppliers lacking rigorous validation capability. At the same time, automation adoption trends are being reinforced by broader industrial modernization objectives in multiple regions, where labor productivity, energy efficiency, and traceability requirements are pushing manufacturers toward integrated servo-mechanical systems. Policy environments that favor automation deployment, machine tool modernization, and local content preferences indirectly expand the addressable base for high precision reducers by accelerating the transition from conventional mechanical drives to precision motion control architectures. The strategic takeaway is that standardization and policy alignment are reshaping the qualification filter: suppliers that can demonstrate compliant test documentation, traceable manufacturing processes, and predictable delivery are gaining preferential access to tenders and long-term automation programs.
Demand-Side Behavior and Application Specificity
End-user behavior is shifting from generic specification purchasing toward application-tuned selection. In robotics, compact motion control demands low-backlash performance and minimal size, pushing suppliers toward integrated servo gear reducers that balance torque density with repeatability. In industrial manufacturing, the emphasis is on torque capacity, serviceability, and integration with higher-level control architectures, favoring product lines that can be configured for a range of ratios and mounting constraints. Semiconductor equipment applications impose a different set of requirements, where cleanliness, thermal steadiness, and micro-positioning reliability determine component selection more than absolute cost. This demand differentiation means that volume growth is increasingly segmented: suppliers that maintain a single generic product strategy face margin compression, while those that engineer for specific application envelopes can command pricing stability and deeper customer lock-in.
Supply Chain Structure and Cost Positioning
Cost structures are being reshaped by localization decisions and assembly sequencing. A notable example is the initiation of local assembly of P2.e planetary gear units in South Carolina, which reduced lead times for cataloged ratios to as short as six weeks. This move illustrates a broader trend: regional assembly capability is becoming a commercial differentiator because it shortens delivery cycles, reduces freight exposure, and improves responsiveness to specification adjustments without requiring full product redesign. At the same time, raw material consistency, heat treatment capacity, and precision machining availability remain binding constraints on output quality. Suppliers are responding by tightening upstream material sourcing, increasing in-house treatment capability, and standardizing modular ratio configurations to reduce custom engineering load. The cost implication is not simply lower unit pricing but lower total cost of ownership for buyers, which is increasingly the decisive factor in multi-year automation programs.
竞争格局与领先策略
The competitive landscape is characterized by moderate concentration, with the top three suppliers accounting for approximately 25% of market revenue and the top five extending to 35%. This distribution leaves substantial room for regional specialists, application-focused entrants, and integrated manufacturers to compete on engineering fit and delivery reliability rather than price alone. The market is not yet consolidating into a handful of dominant players, but it is stratifying around distinct value creation models.
Strategic Positioning Among Leading Suppliers
Leading companies have carved out defensible positions by aligning product architecture with specific application expectations. Neugart GmbH emphasizes low backlash and high rigidity across Economy and Precision Line series, targeting industrial motion control environments where repeatability and mechanical stiffness are paramount. Wittenstein SE competes on low-backlash servo gearboxes and hygienic design variants, positioning itself for demanding applications where cleanliness and precision must coexist. Apex Dynamics Inc. focuses on helical gearing for low backlash and high torque in servo applications, appealing to customers who prioritize torque transmission smoothness within compact envelopes. Harmonic Drive LLC markets zero-backlash planetary gearboxes engineered for robotics and precision actuation, reinforcing a performance-first positioning where elimination of mechanical play is the central value proposition. SEW-EURODRIVE GmbH & Co. KG offers high-torque planetary gear units with ratings up to 124 kNm, addressing industrial and servo applications where load capacity and durability determine system sizing. In parallel, several regionally anchored manufacturers are expanding their visibility through trade engagement and localized engineering support, signaling a market where regional presence, material specifications, and application demonstration increasingly influence procurement decisions.
Differentiation and Margin Protection
Sustainable differentiation in this market rarely comes from a single specification breakthrough; it emerges from the combination of precision validation, application support, and supply responsiveness. Suppliers that can document thermal-stable backlash behavior, provide modular ratio sets, and offer predictable delivery timelines are better positioned to protect margins than those competing primarily on unit price. Engineering services also matter: the ability to advise on mounting configurations, lubrication intervals, and integration with servo drives reduces implementation risk for buyers and increases switching costs. In practice, the most resilient players treat the gear reducer not as a standalone commodity but as part of an integrated motion solution, where documentation, testing evidence, and post-sale technical support reinforce the initial purchase decision.
Robot Joint Precision Reducers Market
Market Evolution: Integration, Fragmentation, and New Entrants
The landscape is evolving along two simultaneous tracks. On one hand, larger industrial drive and transmission groups continue to integrate planetary gearing into broader automation portfolios, leveraging existing distribution channels and application engineering teams. On the other hand, the market remains open to regional specialists and application-focused entrants who can win on precision claims, localized assembly, or domain-specific validation. New entrants are most likely to succeed where they can demonstrate measurable advantages in thermal stability, backlash control, or delivery speed, rather than attempting to compete across the full product spectrum. Consolidation is expected to remain selective, driven by the need to secure material supply, testing capability, and regional service coverage rather than by volume aggregation alone. The practical implication is that competitive advantage will increasingly belong to suppliers who can combine engineering credibility with agile commercial execution.
未来趋势预测
The next three to five years are likely to be defined by tighter performance verification, expanding application reach, and continued localization of supply. These trends create clear commercial opportunities, but they also introduce execution risks that demand disciplined planning.
Thermal-Validated Precision as a Baseline Expectation
Dynamic thermal testing and equilibrium-based verification are likely to move from guideline adherence to purchasing prerequisite. As end-users integrate gear reducers into high-duty-cycle automation systems, they will demand documented performance under sustained loads rather than nominal specifications. Suppliers that invest early in thermal validation infrastructure, repeatable test protocols, and transparent documentation will gain access to higher-value programs and reduce quotation-to-approval friction. The commercial opportunity lies in positioning precision verification as a risk-reduction asset for system integrators and original equipment manufacturers, not merely as a compliance cost. The risk, however, is that validation requirements raise the entry barrier and compress margins for suppliers that cannot efficiently scale testing throughput.
Worldwide Precise Servo Reducer Market
Robotics and Semiconductor-Driven Demand Expansion
Robotics will continue to be a primary volume driver, but high-precision planetary gear demand will increasingly be shaped by semiconductor equipment and advanced manufacturing systems that require micro-positioning reliability and thermal steadiness. This divergence means that growth will not be uniform; it will concentrate in applications where positioning accuracy directly affects yield, throughput, or equipment uptime. Suppliers that build application-specific engineering capabilities for these sectors can secure longer program cycles and more predictable demand. The upside is meaningful, but the downside risk is concentration risk: over-indexing on a single application without diversification can expose a supplier to cyclical downturns or technology substitution if alternative actuation methods gain traction.
Regional Assembly and Lead-Time Competition
Local assembly, modular ratio configuration, and regional distribution will become more important as buyers prioritize fast fulfillment and reduced supply chain uncertainty. The ability to deliver catalog ratios within short lead times is already reshaping purchasing expectations, and this pressure will likely intensify as automation programs accelerate and inventory strategies shift toward just-in-time readiness. Suppliers that establish regional assembly capability, standardize configurable product blocks, and maintain material consistency will be better positioned to capture demand in markets where delivery reliability equates to operational continuity. The associated risk is capital intensity and coordination complexity: regional capacity must be managed carefully to avoid fragmented production quality or excess inventory if demand forecasts shift.
决策者行动建议
Strategic choices in this market should be guided by the recognition that precision, delivery reliability, and application support are becoming as commercially significant as unit cost. The following recommendations are geared toward the main stakeholder groups evaluating exposure to high precision planetary gear reducers.
For Manufacturers and Product Companies
Engineer for application envelopes rather than generic catalogs. Prioritize thermal-stable backlash performance, modular ratio configurations, and documented validation evidence, because these attributes increasingly determine qualification success and pricing resilience. Invest in regional assembly or localized configuration capability where lead time expectations are compressing, and align material sourcing with consistent heat treatment and machining availability to protect quality at volume. Develop application-specific technical support that helps system integrators reduce integration risk, since post-sale engineering value is becoming a differentiator in multi-year automation deployments.
For Investors and Commercial Evaluators
Assess suppliers on verifiable precision capability, testing throughput, and regional delivery infrastructure rather than headline revenue alone. Favor companies that demonstrate modular product architecture, stable material supply, and the ability to shorten lead times for cataloged configurations, because these traits support margin stability and customer retention. Monitor application concentration as a risk indicator: businesses that are heavily dependent on a single sector should be evaluated against the potential for demand volatility or technology substitution, while diversified application portfolios typically offer more resilient growth profiles.
For Buyers and Procurement Teams
Shift evaluation criteria toward total cost of ownership, thermal-stable performance documentation, and delivery reliability. Request verification evidence under dynamic conditions, clarify ratio availability and lead-time expectations for cataloged configurations, and assess supplier capability to support integration with servo control architectures. Prioritize suppliers that can provide predictable delivery and application engineering assistance, because implementation risk and downtime avoidance often outweigh marginal unit price differences in precision automation programs.
For organizations seeking a deeper dive into segment-level sizing, regional dynamics, application demand curves, and competitive benchmarking, the full market research report provides detailed breakdowns and customized strategic recommendations that extend beyond the directional insights outlined here. Accessing that level of granularity can help align investment timing, product planning, and sourcing strategy with the specific demand drivers that will shape the next phase of market growth.
For detailed analysis of this topic, please visit the official page: High Precision Planetary Gear Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bovine Lactoferrin Market 2026: How the 4.3% CAGR and Asia Pacific’s 325.41M Surge Redefine Growth
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Bovine Lactoferrin Market
Market Snapshot and the Structural Inflection Point
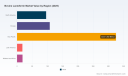
The bovine lactoferrin market has moved from a niche specialty ingredient to a strategically significant component of the global nutrition and health ecosystem. Valued at approximately 378.0 million USD in 2020, the market expanded to 565.08 million USD by 2025, reflecting a compound annual growth rate of 4.3 percent over the 2026-2032 forecast period. Annual revenue is projected to progress from 591.33 million USD in 2026 toward 747.35 million USD by 2032, signaling sustained demand expansion rather than a temporary cyclical uptick.
This trajectory is not uniform across segments or geographies. The market is fragmenting along functional, regulatory, and sourcing lines, creating pockets of high-value growth alongside commodity-like pressure in commoditized supply chains. For executives and investors, the headline growth rate obscures a more nuanced reality: value migration is occurring toward producers who can guarantee purity, traceability, functional consistency, and regulatory clearance across multiple jurisdictions simultaneously.
Several structural challenges and inflection points are reshaping how participants position themselves:
- Functional consistency versus scale tension . Manufacturers face mounting pressure to deliver batch-to-batch consistency in iron-binding capacity, protein integrity, and microbiological profile while scaling output. As demand concentrates in infant nutrition and premium dietary supplements, buyers increasingly treat lactoferrin as a functional active rather than a bulk dairy by-product, raising the cost of quality failures.
- Regulatory divergence as a market filter . Jurisdictional differences in ingredient classification, novel food assessment, and safety notifications are creating asymmetric market access. Companies that can navigate multiple regulatory pathways simultaneously are gaining disproportionate commercial leverage, while those dependent on a single region face constrained expansion options.
- Feedstock volatility and margin sensitivity . High-quality bovine milk feedstock exhibits price volatility tied to seasonal variations, feed costs, and broader dairy market fluctuations. This introduces margin unpredictability for producers and complicates long-term pricing commitments for formulators, particularly in categories where lactoferrin represents a meaningful share of raw material cost.
These dynamics are not merely operational headaches; they are strategic filters. They determine which players can credibly serve premium segments, which can secure multi-year supply agreements, and which are relegated to price-competitive commodity positions.
Key Drivers Reshaping the Market
Precision fermentation and bioprocessing breakthroughs
A defining shift in the market is the emergence of precision-fermented bovine lactoferrin as a commercially viable alternative to milk-derived extraction. In May 2025, TurtleTree received the first FDA no-questions GRAS letter for precision-fermented bovine lactoferrin, enabling broader use in food and supplement applications. Around the same time, the FDA issued a no-questions GRAS letter for recombinant bovine lactoferrin isolate produced by Komagataella phaffii M020. These regulatory milestones matter because they open a supply pathway that is less tethered to dairy feedstock volatility and potentially more scalable for high-purity applications.
The strategic implication is twofold. First, fermentation-based supply expands the addressable market by reducing dependency on milk supply constraints and offering a potentially more controlled production environment. Second, it introduces a new competitive axis: producers of milk-derived lactoferrin must differentiate on native protein attributes, organic certification, and established regulatory status, while fermentation players compete on scalability, purity, and pricing predictability. This does not eliminate dairy-derived lactoferrin; rather, it segments the market into performance- and credential-driven tiers.
Regulatory acceleration and market access realignment
Regulatory developments are simultaneously opening and structuring demand. China eliminated import tariffs on dairy-based formula foods for special medical purposes, effective in late 2023 and continuing into 2025, creating a more favorable environment for specialized nutrition imports. In parallel, the European Union assessed bovine lactoferrin as a food ingredient in 2025 under Novel Food regulation for uses in infant formula, supplements, and sports nutrition. These processes are not just compliance exercises; they redefine which applications can scale and which regions can serve as growth platforms.
Bovine Colostrum Market
For commercial planners, the key insight is that regulatory clarity often precedes demand formalization. Once an ingredient is cleared for specific categories, formulators can invest in product development, claim substantiation, and distribution with reduced regulatory risk. The uneven pace of approvals across regions means that early movers in cleared markets can build brand and supply relationships before competition intensifies.
Demand-side evolution toward functional and clinical nutrition
Consumer and enterprise demand is increasingly shaped by functional outcomes rather than generic protein supplementation. Infant formula remains a central application area, driven by the perceived nutritional and immune-support benefits of lactoferrin for early-life development. Dietary supplements continue to absorb meaningful volume as well, particularly where lactoferrin is positioned around immune health and active wellness. At the same time, interest is expanding into sports nutrition, medical nutrition, and functional food and beverage formats, where lactoferrin's iron-binding and bioactive properties are being repurposed for differentiated product claims.
This demand evolution raises the stakes for ingredient suppliers. Formulators want documentation, stability data, application compatibility, and regulatory support, not just price and bulk availability. The winners are increasingly those who function as application partners, helping customers integrate lactoferrin into complex matrices while maintaining label-claim integrity and sensory acceptance.
Supply chain reconfiguration and capacity investments
Capacity expansion is a visible signal of strategic confidence in the category. Beston Global Food Company Ltd expanded lactoferrin production capacity at its Jervois dairy factory in Australia to up to 25 MT of 95% pure lactoferrin per year. More broadly, the U.S. Department of Energy invested $9.7 million in alternative protein projects, including lactoferrin, to support decarbonization of the food sector in 2025, reinforcing the policy tailwinds behind alternative and lower-impact production routes.
These investments reflect a broader realignment in supply chain thinking. Participants are increasingly weighing feedstock security, geographic diversification, and processing efficiency alongside traditional metrics such as throughput and unit cost. For buyers, this means supply is becoming more modular and regionally distributed, which can improve resilience but also increases the importance of qualification, vendor auditing, and multi-source strategies.
Competitive Landscape and the Emerging Strategic Playbook
The bovine lactoferrin market remains moderately concentrated, with CR3 at 34.2 percent and CR5 at 41.5 percent. This concentration level suggests a landscape where leading players hold meaningful share but no single entity dominates the category outright. The result is a market in which differentiation, application expertise, and regulatory positioning matter as much as sheer scale.
Worldwide 2'-Fucosyllactose (2'-FL) Market
Several patterns distinguish the more strategically advantaged participants:
- Vertical integration from dairy processing to high-value ingredients . Companies rooted in dairy processing are leveraging existing milk supply, quality systems, and co-product economics to produce lactoferrin alongside broader ingredient portfolios. This model can lower effective feedstock risk and provide operational leverage, particularly when lactoferrin is positioned within a wider nutritional ingredients offering rather than as a standalone commodity.
- Specialization in organic and native-grade positioning . A subset of manufacturers is building reputation around native bovine lactoferrin with specific certification profiles, including organic grade for infant nutrition and dry-mix applications. This approach targets premium segments where purity credentials, traceability, and application-specific documentation command higher margins and deeper customer stickiness.
- Process technology ownership and scale leadership . Long-standing technology relationships and proprietary processing approaches remain a durable advantage. One of the largest-volume producers uses Morinaga process technology, illustrating how established production know-how can underpin scale leadership and consistent output. In a category where functional performance depends heavily on processing integrity, technology lineage is a meaningful moat.
- Regional branding and traceability narratives . Some producers emphasize origin-specific attributes, such as Australian whey sourcing or Swiss production, to differentiate in premium markets. These narratives can support pricing power when they are paired with verifiable quality systems and strong documentation, especially in categories where safety and provenance are closely scrutinized.
Strategic developments in 2024 and 2025 point to an accelerating evolution in the competitive map:
- Joint ventures and commercialization partnerships . In December 2025, All G and Armor Protéines formed a joint venture to scale production and commercialization of human and bovine lactoferrin, with All G's first bovine lactoferrin powder product launching in late 2025. This reflects a broader trend in which companies combine complementary capabilities—one partner may bring production or process strengths, while the other contributes market access or application expertise—to reduce time to scale and de-risk commercialization.
- Capital reinforcement for first-mover positioning . In January 2025, All G raised over A$10 million to support commercial-scale production of its first bovine lactoferrin product, with launch targeted for Q1 2026. Capital inflows of this type often signal investor conviction that scale, purity, and timing can translate into defensible market positions, particularly when paired with clear application roadmaps.
- Regulatory milestones enabling category expansion . TurtleTree's FDA GRAS notice and related regulatory activity are lowering barriers for precision-fermented lactoferrin in food and supplement channels. This expands the competitive field by enabling new entrants to pursue applications that previously depended on milk-derived supply and more complex compliance pathways.
- Capacity and purity upgrades among established producers . Beston Global Food Company Ltd's capacity expansion and emphasis on up to 95% purity illustrate how incumbents are responding to premiumization by improving both volume and grade. This is a competitive response to buyers who increasingly evaluate lactoferrin on functional performance and specification consistency rather than price alone.
The market is therefore not simply consolidating or fragmenting; it is stratifying. At one end, price-competitive volume players compete on supply efficiency and broad availability. At the other, capabilities-driven participants compete on regulatory clearance, application support, purity, and brand credibility. Between these poles, partnerships and joint ventures are becoming a practical mechanism for bridging production scale with commercialization reach.
A critical trend to watch is the rise of hybrid supply strategies. As fermentation-based and dairy-derived routes both advance, some downstream buyers will seek multi-source portfolios to balance cost, resilience, and functional requirements. That, in turn, may push ingredient suppliers to develop clearer product-line segmentation, with distinct specifications and value propositions for different end-use categories rather than offering a single undifferentiated lactoferrin product.
Outlook for the Next Three to Five Years
Precision-fermented lactoferrin will move from regulatory novelty to commercial optionality
The 2025 regulatory progress for precision-fermented bovine lactoferrin is likely to translate into a growing set of commercial pilots and selective scale-up over the next few years. The near-term opportunity lies in applications where controlled purity, supply consistency, and reduced dairy feedstock exposure provide tangible value, such as specialized supplements and certain functional food formats. Over time, fermentation routes could pressure margins in commoditizing segments while also expanding total addressable demand by making high-purity lactoferrin more broadly available.
The commercial risk is that fermentation-based supply initially enters at a cost or scale disadvantage in some applications, or faces its own regulatory and consumer-acceptance hurdles in specific markets. Companies will need to track not just approval status, but actual adoption curves, labeling outcomes, and procurement economics before treating fermentation as a full substitute for milk-derived supply.
Demand will increasingly center on documented functionality and application fit
Over the next three to five years, procurement decisions are likely to place greater weight on functional documentation, stability performance, and compatibility with target matrices. Infant nutrition and premium dietary supplements will remain anchor categories, but the growth conversation will also include sports nutrition, medical nutrition, and functional food and beverage formats where lactoferrin is used for differentiated benefits. Suppliers that can provide robust technical support and category-specific solutions will be better positioned to capture value than those competing primarily on volume and price.
Regulatory and geopolitical asymmetry will shape geographic expansion
PW Consulting
Because regulatory pathways and trade conditions are not moving in lockstep, geographic expansion will increasingly require localized regulatory strategy rather than uniform global positioning. Tariff changes, novel food assessments, and import conditions can open or constrain markets with little warning. Participants that build regional regulatory intelligence into their product and supply planning will gain faster market entry and fewer stalled launches. At the same time, feedstock cost volatility and dairy market swings will continue to require pricing and sourcing strategies that can absorb short-term disruption without undermining long-term contract credibility.
Strategic Actions for Decision Makers
For manufacturers and ingredient suppliers
- Define clear product-tier strategies that separate premium, application-specific offerings from volume-oriented supply. Purity, certification, documentation, and application support should be explicitly mapped to the segments where they generate pricing power and customer retention.
- Invest in regulatory and market-access capabilities as a core commercial function. Track GRAS and novel food developments, tariff shifts, and category-specific clearance status in target markets so that product roadmaps are aligned with where demand can realistically scale.
- Evaluate partnerships and joint ventures where complementary strengths accelerate scale or market entry. In a moderately concentrated market, combining process technology, supply access, or application expertise can be more efficient than building every capability internally.
For investors and corporate development teams
- Assess lactoferrin exposure in the context of application mix and supply route resilience rather than top-line growth alone. Value creation will likely accrue to businesses that can protect margins through differentiation, multi-source options, or regulatory positioning, not simply to those with the largest volume footprint.
- Monitor fermentation-based entrants as both competitors and potential partnership candidates. The strategic question is not whether alternative production will matter, but where it will be economically superior and which applications it will unlock first.
- Watch for consolidation signals around capacity, purity upgrades, and commercialization agreements. Joint ventures and targeted capital raises may indicate where the market is moving from early validation toward scaled commercialization.
For procurement and supply chain leaders
- Diversify sourcing strategies across dairy-derived and emerging supply routes where specifications and compliance profiles align with product requirements. Multi-source portfolios can improve resilience against feedstock volatility and regional supply disruptions, provided qualification and documentation are managed rigorously.
- Standardize technical and regulatory evaluation criteria for lactoferrin ingredients. Batch consistency, purity specifications, stability data, and application compatibility should be assessed with the same discipline as cost, especially when lactoferrin supports claim-sensitive formulations.
- Build forward-looking sourcing plans around expected regulatory and capacity changes. As new capacity comes online and regulatory clearances expand, early qualification of alternative suppliers can reduce launch risk and preserve negotiating leverage.
The bovine lactoferrin market is entering a phase in which commercial success is increasingly determined by specificity: specificity of application, of regulatory readiness, of supply strategy, and of value proposition. Broad market growth provides opportunity, but durable advantage will depend on which organizations can translate that growth into differentiated, defensible positions across increasingly segmented demand and supply environments. Detailed segmentation data, company-level capability assessments, and scenario-based market outlooks can sharpen these decisions further, especially for teams weighing entry timing, capacity commitments, and multi-market rollout strategies.
For detailed analysis of this topic, please visit the official page: Bovine Lactoferrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pad Printing Supplies Market: Why 5.65% CAGR Reshapes Industry Dynamics
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Global Pad Printing Supplies Market
The pad printing supplies market has evolved from a niche decorating technique into a critical enabler of mass customization, product identification, and industrial marking across multiple manufacturing verticals. Over the 2020-2025 period, the sector demonstrated steady expansion, reaching a valuation of 182.0 million USD in 2025. Forward projections indicate the market will scale to 267.3 million USD by 2032, supported by a compound annual growth rate of 5.65 percent through the forecast horizon. This trajectory reflects a maturing yet still dynamic landscape where incremental technological improvements, regulatory tightening, and shifting end-user expectations are reshaping competitive priorities. For executives and investors, the market no longer rewards pure volume play; it rewards precision in formulation, compliance readiness, and the ability to integrate consumable supply with automated production workflows.
The growth pattern is not uniform across all segments. Historical momentum has been anchored by established industrial applications, but the forward curve is increasingly influenced by regions and use cases that demand higher durability, stricter chemical compliance, and faster turnaround. The market structure remains moderately fragmented, with the top three players capturing roughly a third of total revenue and the top five accounting for just under half. This concentration level signals a space where scale advantages exist but are not insurmountable, and where differentiated value propositions can still secure meaningful share. The following analysis examines the structural challenges, demand drivers, competitive positioning, and forward trends that will determine which organizations capture the next wave of value.
Market Landscape and Core Challenges
The pad printing supplies market has built its recent growth on a foundation of recurring industrial demand, but the operating environment is being reshaped by three overlapping pressures that decision-makers cannot treat as background noise. The first is the compliance burden surrounding ink chemistry and material safety. Formulators and converters are no longer competing only on adhesion, color fidelity, or drying speed. They are increasingly evaluated against a widening set of regulatory expectations that govern volatile organic compound emissions, restricted substances, and end-use safety. Products intended for toys, consumer electronics, packaging decoration, or medical-adjacent components must pass through certification and documentation requirements that vary by jurisdiction. This raises the cost of entry for new formulations and forces suppliers to treat compliance as a core product attribute rather than a post-launch add-on.
The second challenge is the tension between automation throughput and consumable consistency. As pad printing moves from manual or semi-manual cells to integrated automated lines, the tolerance for variation shrinks. Pad wear, cliché durability, ink viscosity stability, and cup performance become process reliability issues rather than simple replenishments. Manufacturers that upgrade equipment often discover that the limiting factor is not the machine itself but the consistency of the consumables feeding it. This creates a structural demand for higher-grade pads, more stable ink systems, and tighter technical support, while also exposing suppliers that rely on commodity-grade inputs to quality and claim risks.
The third challenge is cost volatility in raw materials and logistics, layered with a shift in buyer behavior toward total cost of ownership. Price-per-liter comparisons are losing relevance in many procurement cycles because they ignore waste reduction, line downtime, rework, and compliance risk. Buyers are increasingly scrutinizing whether a marginally cheaper ink generates higher hidden costs through slower curing, more frequent pad changes, or failed audits. Suppliers that compete primarily on unit price face margin compression, while those that can demonstrate measurable process efficiency and reduced compliance exposure are better positioned to defend their positioning. Together, these challenges reframe the market from a transactional supplies business into a performance and risk-management partnership.
Key Drivers of Market Evolution
Technological Innovation and Formulation Advances
Technology is reshaping the pad printing supplies market along two reinforcing paths: ink performance and process integration. On the ink side, the industry is moving toward systems that balance print quality with environmental and safety constraints. Solvent-based formulations continue to hold a strong position where adhesion and metering stability are critical, but the innovation frontier is increasingly defined by how cleanly those systems can operate and how easily they fit into controlled production environments. UV-curable options have gained relevance where rapid hardening, reduced handling, and energy-efficient processing are priorities, especially in high-speed decorative and marking applications. Ceramic-based inks remain essential for products that must withstand elevated temperatures and harsh surface conditions, maintaining their role in demanding industrial and household contexts. The broader trend is not replacement of one chemistry by another, but the expansion of application-specific toolkits that let manufacturers match consumables to substrate, curing method, and end-use exposure.
Worldwide Specialty Ink Market
Beyond chemistry, the integration of consumables with automation is becoming a differentiator. Suppliers that support custom mixing, automated ink delivery, pad replacement schedules, and cliché management reduce the operational friction that often slows line optimization. When consumables are treated as part of a controlled process rather than as standalone purchases, manufacturers achieve more predictable output and fewer interruptions. This shift is particularly visible in high-volume environments where even small improvements in metering consistency or pad life translate into meaningful throughput gains. The strategic implication is that value is migrating from the mere supply of materials toward the supply of repeatable, documented process performance.
Regulatory and Compliance Pressure as a Market Filter
Regulatory expectations are increasingly functioning as a market filter, shaping both product design and customer selection. Standards and directives associated with chemical safety, restricted substances, and end-use certification are no longer isolated concerns for specific niches. They influence purchasing decisions across packaging decoration, electronics marking, and consumer goods. In practice, this means that documentation, substance control, and test evidence have become commercial assets. Ink systems that can demonstrate alignment with major compliance frameworks reduce the burden on downstream manufacturers and lower the risk of downstream audit failures or product holds.
Recent market activity illustrates this shift clearly. One major supplier introduced a solvent-based and sustainable pad printing ink system designed to support recycling of recovered packaging materials while maintaining durability for toys, electronics, automotive components, and promotional items. The same offering was positioned as free from phthalates and BPA and suitable for printing on the non-food contact side of packaging, with conformance claims tied to multiple regulatory frameworks. Separately, another supplier achieved certification for a group of eco-focused pad printing inks, emphasizing freedom from naphtha, PAH, and cyclohexanone, with compliance references to REACH, RoHS, and EN 71-3. These moves are not isolated product launches; they signal a broader market dynamic in which environmental and safety credentials are becoming decision-critical, especially where procurement teams must justify material choices to internal stakeholders and external auditors alike.
Digital Textile Printing Ink Market
Demand-Side Shifts in Manufacturing and Branding
Demand is being shaped by a combination of industrialization, product complexity, and brand expectations. Manufacturers are printing more than logos; they are applying identification marks, functional labels, safety information, and decorative finishes that must survive handling, cleaning, and time. The growth of short-run customization and rapid product variation also increases the value of flexible pad printing supplies that can adapt to frequent changeovers without sacrificing quality. In electronics, smaller components and tighter tolerances increase the need for precise deposition and stable ink behavior. In glass and plastic products, surface diversity demands inks and pads that can maintain adhesion across varying textures and finish types. In ceramic and porcelain applications, the need for durability under heat and moisture keeps specialty ink systems relevant.
At the same time, downstream brands and contract manufacturers are placing greater weight on process reliability and material documentation. Procurement is increasingly influenced by the need to reduce variability across shifts, minimize rework, and avoid supply-chain surprises caused by reformulation or compliance gaps. This makes supply consistency, technical support, and change-management capability more valuable than ever. Buyers are not simply purchasing pads, inks, and plates; they are purchasing predictability.
Supply Chain and Cost Structure Realignment
Cost structure is being rethought around durability, waste, and support rather than headline price. Volatile input costs and logistics uncertainty have made it harder for suppliers to compete on discount alone, while buyers are more willing to pay for solutions that reduce line waste or improve uptime. The result is a gradual realignment toward value-based positioning, where suppliers justify their pricing through measurable operational benefits. This also favors companies with stronger technical service models, more controlled formulation pipelines, and the ability to provide custom mixes or region-specific compliance support. For customers, the supply chain is becoming a source of process advantage rather than just a procurement function.
Competitive Positioning and Strategic Differentiation
The competitive landscape is defined by a mix of established ink and consumables specialists, regional machine-and-consumable integrators, and suppliers that combine equipment, tooling, and consumables under one roof. The distinct strategic advantage in this market is rarely derived from a single product feature. It is built from the combination of formulation capability, compliance readiness, automation support, and service responsiveness. Companies that treat pad printing supplies as a system rather than a commodity are better positioned to retain customers through line upgrades, regulation changes, and application expansion.
On the ink and consumables side, several players are competing on specialized chemistry and certification strength. One German-based supplier maintains a broad portfolio covering inks, clichés, printing pads, ink and doctoring cups, auxiliary materials, and laser cliché production, positioning itself as a full-line provider for pad printing operations. Another German formulates a wide range of solvent-based and UV-curable inks oriented toward industrial decoration, marking, and identification, emphasizing breadth across application types. In the United States, a major international supplier has pushed eco-oriented formulations, including solvent-based and UV pad printing inks designed without phthalates or BPA for packaging and product decoration, appealing to buyers who need both performance and cleaner substance profiles. A separate U.S. consumables specialist has emphasized eco-certified formulations, with a portion of its SB Eco Series inks achieving GOTS certification and aligning with REACH, RoHS, and EN 71-3 requirements. This certification-driven positioning is strategically important because it converts compliance into a marketable advantage rather than a hidden cost.
A second competitive cluster revolves around integration with equipment and automation. One U.S. supplier focuses on custom pad printing machines, tooling, fixtures, and consumables for high-volume automated applications, effectively combining hardware and consumables to reduce sourcing complexity. Another U.S. player offers a wide range of pad printing machines, fixtures, inks, pads, printing plates, and operates a large North American ink warehouse, leveraging distribution scale and inventory depth as a service advantage. A silicone and consumables-focused supplier produces in-house silicone pads, inks, plates, fixtures, and accessories, giving it tighter control over the pad supply chain and a direct route to custom specifications. Yet another U.S. company emphasizes custom-mixed inks, printing pads, cliché plates, and full automation support, highlighting the importance of flexibility in demanding production environments.
The competitive pattern suggests two parallel value routes. The first is depth in formulation and compliance, where differentiation comes from certification, substance control, and application-specific ink performance. The second is breadth and integration, where differentiation comes from equipment compatibility, inventory availability, custom mixing, and process support. Companies that can bridge both routes, even partially, gain a stronger hold on customers because they reduce the number of separate sourcing decisions and make it easier to standardize across multiple lines or sites.
Market structure is likely to evolve through selective consolidation and targeted specialization rather than across-the-board merger activity. Larger players with distribution scale and compliance infrastructure can absorb smaller regional suppliers or geographic distributors, especially where customers value single-source reliability. At the same time, niche specialists can prosper by owning a specific application, chemistry, or certification niche that larger generalists cannot serve as precisely. New entrants face a meaningful barrier in formulation know-how, certification timelines, and established technical service relationships, but they can still gain traction by addressing underserved compliance needs or automation-centric consumable packages. The most durable strategy appears to be building defensible positioning through either regulatory readiness and documented performance, or integrated automation support and customizability, while avoiding reliance on price alone.
Forward Trends and Commercial Implications
Compliance and Eco-Aligned Formulations Will Become Baseline Expectations
Over the next three to five years, the market is likely to see compliance-friendly and lower-impact formulations move from premium differentiators to baseline requirements in many application areas. Buyers serving consumer-facing, electronics, and packaging-adjacent markets will increasingly expect substance control, test evidence, and documentation as standard deliverables. This trend favors suppliers with established certification pathways and formulation discipline, while raising the risk for those that treat compliance as reactive. The commercial opportunity lies in building repeatable compliance narratives that simplify customer purchasing and reduce audit friction. The uncertainty is that regulatory expectations can diverge by region and application, creating a moving target for global suppliers and requiring localized documentation strategies.
Automation-Ready Consumables and Process-Locked Partnerships
As more production lines adopt higher levels of automation, consumables will be evaluated for their behavior inside controlled systems rather than in isolation. This should increase demand for inks and pads that support consistent metering, stable curing or drying, predictable wear, and easier integration with auto-ink delivery or changeover workflows. Suppliers that provide custom mixing, process tuning, and technical support will be better positioned to lock in long-term relationships, because the value they deliver is tied to line performance rather than unit transactions. The opportunity is to design consumables and service packages that reduce downtime and variability. The risk is that automation increases the stakes of inconsistency; a single recurring failure mode can erode trust quickly and push buyers toward more controlled supply alternatives.
Application Expansion and Regional Rebalancing
Forward growth is likely to be supported by continued application expansion across glass and plastic products, ceramic and porcelain items, electronic components, and other industrial uses, with regional demand patterns shifting as manufacturing footprints and export channels evolve. Regions with expanding industrial output, packaging activity, and consumer goods production will create incremental demand for marking, decoration, and identification supplies. The commercial opportunity is to align product portfolios and service coverage with the applications and geographies that are scaling fastest, rather than assuming legacy demand patterns will persist unchanged. The downside is that regional expansion can expose suppliers to new compliance regimes, logistics constraints, and competitive responses, making localized positioning and supply resilience more important than generic global messaging.
Actionable Implications for Decision-Makers
For manufacturing and operations leaders, the priority is to treat pad printing supplies as a process variable with measurable business impact. Procurement should evaluate ink systems, pads, and cliché solutions against line throughput, waste, changeover time, and compliance exposure, not just purchase price. Where production is moving toward higher automation or stricter end-use requirements, teams should prioritize suppliers that can provide documented performance, stable formulation pipelines, and responsiveness to custom specifications. Establishing clear acceptance criteria for consistency and certification documentation can reduce the risk of downstream failures and make supplier comparisons more objective.
For investors and corporate development teams, the market presents opportunities in players with credible compliance positioning, formulation depth, and integration with automation-focused customers. Businesses that have built certification readiness, custom-mixing capability, or strong regional distribution and inventory support are better placed to defend margins and capture share from purely transactional competitors. At the same time, due diligence should account for regulatory variability, raw-material exposure, and the durability of customer relationships beyond single projects. The most attractive profiles typically combine technical differentiation with recurring consumable demand and clear alignment to end-use compliance needs.
PW Consulting
For procurement and sourcing professionals, the strategic task is to move from transactional purchasing to supplier partnership models that reduce total operating risk. That includes evaluating eco-oriented and certified formulations where relevant, aligning consumable selection with equipment and line requirements, and ensuring that documentation and compliance claims are part of the sourcing decision. Where multiple sites or product families are involved, standardization on a smaller set of validated consumables can improve consistency and simplify audits, provided the selected options remain flexible enough for application-specific needs. In markets where compliance expectations are rising, sourcing decisions made without adequate documentation can create hidden cost and operational risk.
For organizations seeking deeper segmentation data, company-level positioning, and scenario-based guidance across regions and applications, the full PW Consulting market research report provides a more detailed breakdown of revenue splits, competitive profiles, and forecast assumptions. The report supports more precise planning by extending the core market view into actionable detail for procurement strategy, investment screening, and long-range capacity or portfolio decisions.
For detailed analysis of this topic, please visit the official page: Pad Printing Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Drive Shaft Market 2026: Beyond The 5.2% CAGR—Strategic Shifts Reshaping Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Automotive Drive Shaft Market
The automotive drivetrain is undergoing one of its most significant structural transformations in decades. As propulsion architectures diversify and vehicle platforms evolve, the drive shaft has shifted from a standardized mechanical component to a strategically differentiated element of vehicle performance, efficiency, and packaging. Market tracking indicates that the global automotive drive shaft sector has grown from approximately $6.9 billion in 2020 to an estimated $9.03 billion in 2025, with a projected compound annual growth rate of 5.2 percent across the 2026–2032 horizon. The trajectory points toward a market surpassing $12.8 billion by the end of the forecast period, reflecting both volume expansion and a steady shift toward higher-performance, lightweight, and application-specific designs.
Beneath the headline growth figures lies a more nuanced reality. The sector is no longer driven solely by total vehicle production; it is increasingly shaped by propulsion mix, regional platform strategies, material substitution, and the consolidation of driveline technology portfolios. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where value is being created, which capabilities are becoming non-negotiable, and how prevailing cost and regulatory pressures will reshape competitive dynamics over the next five years.
Market Landscape and Core Challenges
The current market structure reflects a maturing but directionally shifting ecosystem. Growth over the historical period was supported by steady passenger vehicle demand, incremental content gains in vehicle platforms, and early-stage electrification programs that required rethinking torque delivery and packaging constraints. The commercial vehicle segment continues to provide meaningful volume stability, while the passenger car segment anchors the majority of revenue. Within product categories, hollow shaft designs dominate the revenue split, driven by their weight advantages, torsional efficiency, and broader adoption in modern front-wheel and all-wheel-drive architectures. Solid shafts retain a strong presence where durability, load capacity, and cost predictability remain paramount, particularly in heavier commercial applications and certain rear-drive configurations.
Worldwide Intermediate Shaft for Vehicle Market
Against this backdrop, three core challenges are reshaping how suppliers, OEMs, and investors should read the market.
- Propulsion-mode fragmentation. The transition from conventional internal combustion architectures to hybrid and electric platforms is not a 1:1 replacement of existing driveline content. Electric and hybrid vehicles alter torque characteristics, packaging envelopes, and NVH requirements, forcing suppliers to redesign joint interfaces, support structures, and shaft geometries. This creates short-term engineering complexity and lengthens validation cycles, even as it opens longer-term opportunities for propulsion-agnostic driveline systems.
- Material cost volatility and sourcing pressure. Steel continues to serve as the foundational material for many drive shaft applications because of its balance of strength, toughness, and supply chain maturity. At the same time, aluminum and composite solutions are gaining ground where weight reduction and efficiency targets are most stringent. The practical challenge is that raw material price swings for steel, aluminum, and composites can push component costs upward by as much as 15 percent in a single year, complicating quotation stability, margin planning, and long-term program commitments.
- Competitive concentration with room for differentiation. The market remains relatively fragmented at the top, with the leading three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. That level of concentration signals a sector where scale, customer relationships, and engineering breadth matter, but also where differentiation is still possible through application-specific engineering, regional manufacturing footprints, and value-added design services. In practical terms, market share alone does not guarantee resilience unless it is paired with program wins in higher-growth configurations and cost-competitive execution.
Key Demand Drivers
Technology Innovation and Design Breakpoints
The most consequential driver of near-term market change is the engineering redefinition of what a drive shaft must accomplish. Lightweight aluminum and carbon fiber composites are increasingly specified by EV manufacturers as standard options to meet efficiency and emissions requirements, signaling a structural shift in component specifications rather than a temporary trend. This push toward weight reduction intersects with higher torque density in electrified powertrains, which places new demands on joint durability, balance, and vibration damping. Suppliers that can deliver hollow shaft designs with tighter tolerances, optimized wall profiles, and advanced joint integration are better positioned to capture content in vehicles where every kilogram and every decibel of NVH performance matters.
Technically, the opportunity is not limited to material substitution. The growth of high-angle CV joints, telescopic solutions, and integrated driveline architectures reflects a broader demand for packaging flexibility in crossovers, EVs, and premium passenger vehicles. Product launches in this space are increasingly framed around supporting multiple propulsion types within a single platform strategy, which suggests that future winning components will be judged as much on adaptability as on baseline performance.
Policy and Regulatory Environment
Regulatory expectations continue to influence design choices indirectly but powerfully. Efficiency mandates, emissions targets, and durability standards create incentives for weight reduction, friction reduction, and longer service life. In electric vehicle programs, these requirements can translate into more aggressive use of aluminum and composites, as well as tighter specifications for rotating components. The regulatory environment also affects commercial vehicle demand, where emissions and payload considerations shape axle and driveline selection. While policy does not prescribe a single drivetrain architecture, it consistently raises the cost of inefficiency, which benefits suppliers capable of delivering lighter, more integrated, and more reliable driveline solutions.
Demand-Side Shifts in Consumer and OEM Behavior
On the demand side, the expansion of SUVs, crossovers, and premium passenger vehicles has increased the relevance of driveline systems that can accommodate varied packaging constraints and higher performance expectations. Passenger cars continue to represent the dominant revenue base, but the composition of that demand is changing. OEMs are prioritizing platforms that can be reused across propulsion types, which favors suppliers with modular, propulsion-agnostic capabilities. At the same time, commercial vehicle demand remains a critical anchor for solid shaft and heavy-duty applications, particularly where strength, load capacity, and total cost of ownership outweigh the emphasis on minimal weight.
The commercial-vehicle side also introduces a different purchasing logic. Fleet operators and commercial OEMs focus heavily on lifecycle cost, serviceability, and reliability under sustained load. That creates a dual-track market: one track oriented toward efficiency and lightweight integration in passenger vehicles, another oriented toward robustness and cost predictability in commercial applications. Suppliers that can manage both tracks without diluting engineering focus tend to be more resilient across cycles.
Supply Chain and Cost Structure Dynamics
Cost structure is becoming a strategic battleground. Established steel supply chains provide reliability and scale, but they are exposed to price volatility and regional availability constraints. Aluminum and composites can improve performance and packaging, yet they introduce additional complexity in sourcing, processing, and validation. The practical consequence is that cost competitiveness is increasingly determined not just by material choice, but by supplier integration, manufacturing efficiency, and the ability to manage mix shifts without sacrificing delivery reliability. Programs that require rapid transitions between material grades or joint configurations amplify the importance of flexible production and strong supplier relationships.
This environment favors suppliers that can combine engineering support with disciplined cost execution. In practice, the winners are those who can help OEMs navigate the trade-offs between weight, strength, NVH, and cost while keeping programs on schedule. That is especially true as recent industry developments show major players investing in driveline technologies that span EVs and conventional platforms, indicating that breadth of capability is becoming a commercial advantage.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established driveline specialists, each with a distinct strategic posture. GKN Automotive remains focused on sideshafts, CV joints, and propeller shafts across ICE, hybrid, and electric vehicles, emphasizing propulsion-agnostic drive systems. That positioning reflects an effort to stay relevant across propulsion transitions rather than betting on a single powertrain future. Nexteer Automotive has built a reputation around premium telescopic drive shafts and high-angle CV joints for OEM applications, with a recent emphasis on driveline technologies designed to support both EVs and premium driving experiences across propulsion types. In the first quarter context, Dana Incorporated reported strong results alongside new business wins in drivetrain solutions, illustrating how program-level victories can reinforce commercial momentum even as broader market conditions remain mixed.
The competitive picture also includes major driveline and metal-forming players such as American Axle & Manufacturing, which supplies front and rear axles and driveshafts for global OEMs, and Hyundai WIA Corporation, which produces driveline systems and drive shafts for both passenger and commercial applications. Neapco Holdings rounds out the landscape with driveline components including driveshafts and CV joints for OEM and aftermarket use. Together, these companies highlight a market where scale, geographic reach, and application coverage matter, but differentiation increasingly depends on engineering integration and program execution.
Recent corporate and product activity underscores how the landscape is evolving. The announcement of a combination involving Dauch Corporation and Dowlais Group, integrating GKN Automotive driveline technologies, signals a consolidation path aimed at broadening technical portfolios and strengthening competitive scale. At the same time, product-level moves such as Nexteer’s introduction of three driveline technologies for EVs and premium applications show that innovation remains a central competitive lever. The pattern suggests a market that is neither fully consolidated nor static; rather, it is being shaped by selective integration, technology broadening, and continued investment in next-generation driveline architectures.
Strategic differentiation is emerging along several axes. One is propulsion-agnostic engineering: the ability to support multiple powertrain types with shared platform logic reduces OEM complexity and increases the value of suppliers that can deliver flexible component families. Another is material and design leadership, especially where lightweight solutions can be adopted without compromising durability or cost targets. A third is regional manufacturing and customer proximity, which supports faster response times, lower logistics exposure, and better alignment with local content expectations. In this environment, scale alone is inadequate; competitive advantage is increasingly tied to technical breadth, portfolio coherence, and the capacity to convert innovation into repeatable program wins.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Propulsion-Agnostic Driveline Architectures Will Become a Standard Expectation
Over the next three to five years, OEMs are likely to continue prioritizing platforms that can accommodate multiple propulsion modes. That dynamic favors drive shaft and driveline solutions that can be adapted across ICE, hybrid, and electric applications without sacrificing performance or packaging efficiency. The commercial opportunity lies in offering modular component families, joint configurations, and integration support that reduce redesign effort and accelerate time-to-production. Suppliers that can demonstrate flexibility without compromising quality or cost structure will be better positioned to secure multi-program relationships.
The associated risk is execution complexity. Supporting diverse propulsion modes increases engineering workload, validation requirements, and inventory complexity. Companies that overextend across too many configurations without disciplined platform logic may face margin erosion and operational strain.
Trend 2: Lightweight Materials Will Expand, but Steel Will Remain Foundational
Industry direction points toward broader adoption of aluminum and composite solutions in applications where efficiency targets and packaging constraints are most demanding. At the same time, steel’s strength, toughness, and established supply chain will keep it central to many drive shaft applications, particularly where cost, durability, and volume manufacturing reliability matter most. The commercial opportunity here is not a simple swap from one material to another; it is the ability to offer the right material choice for each application while managing volatility in raw material costs. Suppliers with strong sourcing strategies, material expertise, and cost-forecasting discipline can convert material transitions into differentiated value rather than margin risk.
A key uncertainty is the pace and consistency of material adoption. If lightweight material specifications become more standardized across EV platforms, adoption could accelerate quickly and reward early movers with strong process capability. If volatility in raw material pricing persists, OEMs may adopt a more cautious stance, prioritizing total cost of ownership over absolute weight reduction in certain segments.
Trend 3: Consolidation and Portfolio Broadening Will Reshape Competitive Access
The market is likely to continue experiencing selective consolidation and portfolio integration as companies seek broader driveline capabilities, greater scale, and stronger positions across propulsion types. This creates two related opportunities. For larger players, integration can expand technical coverage and improve competitive positioning in high-value programs. For smaller or more specialized suppliers, the opportunity lies in focusing on niches where application knowledge, speed, or regional proximity creates defensible value. Investors and executives should watch for combinations that deepen technology portfolios, as well as for supplier strategies that emphasize end-to-end driveline integration rather than single-component competition.
The risk is that consolidation can also raise customer concentration concerns and reduce flexibility in some procurement relationships. Buyers may need to balance the benefits of integrated supply against the desire for multi-source resilience, especially in programs where supply continuity is critical.
PW Consulting
Actionable Guidance for Decision-Makers
For Manufacturers and Suppliers
Focus engineering investment on propulsion-agnostic designs and lightweight material capabilities, but pair that investment with disciplined cost management. The market is rewarding suppliers that can support multiple propulsion types while maintaining stable quotations and reliable delivery. Strengthen program-management and validation capacity so that new product introductions do not become bottlenecks. Where possible, build modular component strategies that reduce redesign risk and enable faster response to OEM platform decisions.
For Investors
Evaluate exposure not just by market size, but by technology breadth, application mix, and sensitivity to material cost volatility. Companies with strong positions in high-growth configurations, diversified propulsion coverage, and credible integration strategies are better placed to capture the next phase of growth. Monitor corporate consolidation activity closely, since combinations that broaden driveline portfolios may change competitive intensity and margin dynamics. Be mindful that revenue growth can mask uneven profitability if material volatility or program mix shifts are not managed effectively.
For Procurement and OEM Sourcing Leaders
Treat supplier selection as a multi-factor decision that includes technical flexibility, material strategy, and regional execution capability, not only unit price. Given raw material volatility, consider sourcing frameworks that provide visibility into cost drivers and allow for structured adjustments without destabilizing program economics. Where lightweight materials are specified for efficiency or emissions reasons, ensure that suppliers have validated processes and sufficient capacity to support scale-up. Diversifying across propulsion-capable suppliers can reduce program risk, especially when platform strategies span multiple powertrain types.
Closing Perspective
The automotive drive shaft market is moving from a period of steady volume-driven growth into a phase where technology choice, propulsion mix, material economics, and supplier integration matter as much as overall demand. The sector’s expansion toward the $12.8 billion range by 2032 is meaningful, but the more important story is how value is being redistributed across product types, applications, and competitive positions. Companies that can align engineering flexibility with cost discipline, while navigating material volatility and shifting propulsion requirements, are the ones most likely to convert market growth into durable advantage.
For decision-makers seeking a sharper read on regional dynamics, application-level demand patterns, material segment shifts, and company-specific positioning, a more detailed research asset can provide the granularity needed to translate these trends into procurement, investment, and product strategy. A full market report offers deeper segmentation detail, competitive benchmarking, and scenario-based guidance tailored to specific business decisions, making it a practical next step for teams that need to move from strategic direction to execution.
Cardan Shaft Market
For detailed analysis of this topic, please visit the official page: Automotive Drive Shaft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Methyl Methacrylate Market
The global methyl methacrylate (MMA) market has entered a period of structural transformation, driven by shifting capacity dynamics, evolving sustainability mandates, and expanding downstream applications. Valued at approximately 162.5 million USD in 2025, the market reflects steady expansion from 113.25 million USD in 2020, with a projected compound annual growth rate of 7.9 percent through 2032. This trajectory signals robust underlying demand, yet the growth path is neither uniform nor frictionless. Industry participants must navigate supply chain reconfigurations, regional price volatility, and intensifying competitive pressures while aligning product portfolios with emerging end-use requirements. Understanding the interplay between technological advancement, regulatory shifts, and demand-side evolution is essential for capturing value in the coming years.
The market concentration remains notably high, with the top three players holding roughly 65 percent of global capacity and the top five accounting for an estimated 85 percent. Such concentration shapes pricing dynamics, influences capacity expansion decisions, and creates both barriers and opportunities for new entrants. While the monomer remains the dominant form consumed across applications, the broader methacrylate ecosystem encompasses a range of derivatives that extend value creation beyond raw monomer supply. Companies that successfully integrate upstream efficiency with downstream formulation expertise are positioned to command stronger margins and deeper customer relationships.
Market Scale and Growth Trajectory
The historical expansion of the MMA market demonstrates consistent growth punctuated by cyclical supply disruptions and regional demand fluctuations. The transition from 2020 through 2025 saw incremental gains as downstream sectors resumed activity following global disruptions, while the forecast period through 2032 points toward accelerated expansion fueled by infrastructure investment, electrified mobility adoption, and electronics miniaturization. Growth is not evenly distributed across regions or applications, but the aggregate trajectory reflects a market that is repricing itself around sustainability premiums, supply reliability, and application-specific performance requirements.
Revenue projections indicate that the market will surpass 180 million USD by 2026 and continue climbing toward 272.5 million USD by 2032. This expansion reflects both volume growth and structural shifts in product mix, as high-performance grades and sustainably produced variants capture a larger share of downstream spending. The pace of growth will depend on how quickly capacity transitions align with demand signals, how regulatory frameworks shape production economics, and how quickly end-use industries adopt next-generation materials.
Key Challenges and Inflection Points
Several structural challenges are redefining the MMA market landscape. First, the transition from traditional C3-based production pathways to alternative feedstock routes introduces both operational complexity and capital intensity. Companies investing in newer production technologies must manage ramp-up risk, supply chain adaptation, and customer qualification timelines, all while maintaining competitive pricing in a market sensitive to raw material spreads.
Second, regional capacity realignment is reshaping supply reliability and pricing architecture. Strategic plant closures, capacity transfers, and geographic shifts in production footprint have altered regional supply balances, creating short-term volatility and forcing downstream buyers to recalibrate sourcing strategies. The interplay between legacy capacity retirement and new facility commissioning has produced uneven supply conditions that reward agile procurement and penalize rigid long-term contracting.
Third, sustainability compliance and carbon footprint differentiation are emerging as decisive commercial factors. End-use industries increasingly demand materials with lower lifecycle emissions, verified recycling integration, and transparent environmental reporting. Producers that cannot demonstrate credible sustainability performance risk losing share to competitors with lower-carbon production pathways or stronger ESG credentials. This dynamic is particularly pronounced in construction, automotive, and electronics, where regulatory pressure and corporate sustainability targets are accelerating material substitution decisions.
Key Drivers Reshaping the Market
Technological Innovation and Production Pathways
Technological advancement remains a primary catalyst for market evolution. Alternative production routes that utilize different feedstock inputs are gaining traction, offering potential advantages in carbon intensity, feedstock flexibility, and integration with circular material flows. One notable development involves the commercialization of a C2-based production pathway that integrates chemical recycling for closed-loop operations, reducing the carbon footprint associated with traditional MMA synthesis. The successful ramp-up of full industrial-scale operation at a major North American facility signals a shift toward lower-emission production models, provided that feedstock availability, operational reliability, and cost competitiveness can be sustained.
Such innovations are not merely technical achievements; they alter competitive positioning by enabling producers to differentiate on sustainability credentials, supply reliability, and long-term cost structure. Companies that can validate performance at scale, secure feedstock partnerships, and communicate environmental benefits to downstream customers are likely to capture premium positioning. Conversely, reliance on legacy production methods without parallel sustainability investments may expose suppliers to margin compression as buyers prioritize lower-carbon alternatives.
Policy and Regulatory Environment
Regulatory frameworks and policy signals are exerting growing influence on capacity planning, feedstock selection, and regional investment decisions. Environmental compliance requirements, emissions reporting mandates, and sustainability-related procurement standards are reshaping the cost calculus for both producers and downstream users. In some cases, regulatory uncertainty has prompted reassessment of large-scale capacity projects, with firms pausing or redirecting investments as they evaluate long-term policy trajectories and market demand alignment.
At the same time, sustainability-driven regulations are creating incentives for process innovation and material efficiency. Producers that proactively align operations with emerging compliance expectations can reduce future retrofit risk and position themselves as preferred suppliers for customers facing their own sustainability mandates. The regulatory landscape is therefore not simply a constraint; it is a filter that rewards operational agility and penalizes complacency.
Demand-Side Evolution and Application Expansion
Downstream demand patterns are shifting as end-use industries pursue performance, lightweighting, and durability improvements. The automotive sector continues to drive volume through applications that require transparent, weather-resistant, and impact-tolerant materials, with electric vehicle platforms creating additional demand for specialized acrylic components and interior trim solutions. Construction activity, supported by infrastructure renewal and modernization initiatives, sustains demand for signage, glazing, and durable surface materials that benefit from MMA-derived performance characteristics.
Electronics and medical applications represent additional growth vectors. Electronics manufacturers are increasingly relying on high-purity acrylic materials for components that demand dimensional stability, optical clarity, and thermal resistance. Medical device and healthcare applications are expanding as biocompatible and sterilizable acrylic materials gain acceptance in diagnostic, procedural, and consumer health products. These application segments are not only adding volume; they are also elevating the value of specialized grades, which command stronger margins and require closer technical collaboration between suppliers and end users.
Supply Chain Dynamics and Cost Structure
Supply chain conditions and raw material cost movements are directly influencing pricing stability and margin outcomes. Global MMA prices experienced upward pressure in early 2026, with momentum intensifying toward the end of the quarter as supply tightened and production costs increased. Such price dynamics highlight the sensitivity of the market to feedstock availability, energy costs, and production utilization rates. Companies that manage feedstock sourcing, energy efficiency, and inventory positioning effectively are better equipped to navigate price volatility and protect margins.
PW Consulting
Capacity realignment across key regions has further complicated supply reliability. Strategic decisions to close certain legacy facilities while commissioning newer, more efficient plants have altered regional supply balances, creating temporary dislocations and forcing downstream buyers to adapt sourcing strategies. In parallel, some producers have adjusted product offerings and geographic sales strategies to optimize portfolio performance, reflecting a broader trend toward disciplined capacity management and targeted market participation.
Competitive Landscape and Leading Strategies
The MMA market is characterized by a concentrated set of global producers, each pursuing distinct strategic priorities to defend or expand their market position. Leading players are differentiating through a combination of production technology, geographic footprint, sustainability commitments, and application-specific product development. The competitive environment rewards scale, operational excellence, and the ability to align supply capabilities with evolving downstream requirements.
Strategic Positioning of Major Players
Major producers are pursuing multiple levers to strengthen competitive advantage. One prominent global producer has focused on expanding its methacrylate leadership through large-scale capacity investments and technology differentiation, maintaining a dominant position in global methacrylate production. Another key player has advanced sustainability-oriented production approaches, emphasizing lower-carbon pathways and closed-loop operations to appeal to customers with stringent environmental targets. Integrated producers supplying monomer and derivatives for coatings, adhesives, and polymer applications are leveraging vertical integration and technical service capabilities to deepen customer relationships and stabilize demand.
Regional presence and supply chain resilience are also central to competitive positioning. Producers with North American operations have invested in capacity expansions and facility modernizations to strengthen regional supply reliability, while Asian-focused manufacturers have adjusted pricing and product strategies in response to regional market conditions. Companies with dedicated division structures for MMA and acrylic resins are increasingly emphasizing high-performance grades for electronics, automotive, and optical applications, reflecting a strategic shift toward value-added segments rather than commodity volume competition.
Specialist producers focusing on methacrylate derivatives and sustainable PMMA solutions are carving out niches by combining application expertise with environmental credentials. Their strategy often centers on technical customization, supply consistency, and sustainability reporting that resonates with downstream customers facing procurement mandates. Meanwhile, global distributors and suppliers of methacrylate-based systems for coatings, adhesives, and polyurethane applications are expanding their geographic reach and product portfolios to capture demand across diverse end-use markets.
Poly Methyl Methacrylate (PMMA) Market
Market Evolution and Competitive Dynamics
The competitive landscape is evolving along several axes. Consolidation and capacity optimization are enabling established players to streamline operations, retire less efficient assets, and redirect capital toward higher-return projects. At the same time, the emergence of alternative production technologies and sustainability-focused differentiation is creating space for companies that can operationalize new pathways at scale. New entrants face meaningful barriers due to capital intensity, feedstock logistics, customer qualification requirements, and the prominence of incumbent technical service networks, but targeted entry into specialty grades or regional supply gaps remains plausible for well-positioned organizations.
Pricing power and margin resilience are increasingly tied to sustainability credentials, supply reliability, and application-specific expertise. Producers that can demonstrate consistent performance, lower lifecycle emissions, and responsive technical support are better positioned to negotiate favorable commercial terms and retain customers during supply disruptions. The market is therefore moving toward a more value-driven competition model, where volume alone is insufficient to secure long-term advantage.
Future Outlook and Emerging Opportunities
Trend 1: Sustainability as a Structural Differentiator
Lower-carbon production and circular material integration are set to become central competitive dimensions over the next three to five years. Producers that successfully scale alternative feedstock routes, chemical recycling integration, and verified emissions reductions will gain preferential access to customers with sustainability procurement mandates. This trend creates opportunities for suppliers to command premiums for certified low-carbon grades, secure long-term commitments from environmentally focused end users, and differentiate from competitors reliant on higher-emission pathways. The risk lies in greenwashing exposure and the need for credible verification, as downstream buyers increasingly scrutinize sustainability claims and demand transparent reporting.
Trend 2: Regional Supply Rebalancing and Sourcing Strategy Shifts
The ongoing realignment of production capacity across regions will continue to influence pricing, availability, and contract structures. As legacy facilities are retired and newer plants reach full operational scale, regional supply balances will evolve, creating both disruption and opportunity. Buyers that diversify sourcing, develop contingency supply arrangements, and align contract terms with capacity transition timelines will be better insulated from volatility. Producers that can offer reliable regional supply, flexible delivery models, and transparent capacity reporting will strengthen their negotiating position and customer retention.
Trend 3: Application Specialization and High-Performance Grade Expansion
Demand for specialized acrylic materials in automotive, electronics, medical, and advanced construction applications is expected to grow as performance requirements become more stringent. This trend favors producers with strong formulation capabilities, technical service infrastructure, and the ability to co-develop solutions with end users. Opportunities exist for suppliers to capture higher margins through grade customization, application-specific certification, and integrated product systems that address multiple performance criteria. The risk is that overinvestment in unproven application segments or inadequate technical support could limit returns, particularly if downstream adoption timelines extend or substitution alternatives emerge.
Methacrylic Acid (MAA) (CAS 79-41-4) Market
Actionable Insights for Decision Makers
The evolving MMA market environment requires proactive strategy adjustments across the value chain. Decision makers should align sourcing, investment, and product development plans with the structural trends shaping supply, pricing, and sustainability expectations.
- For manufacturers and producers, priority should be placed on operationalizing lower-carbon production pathways, securing feedstock and energy cost advantages, and building technical service capabilities that support application-specific sales. Investing in scale where it delivers cost and sustainability benefits, while maintaining disciplined capacity management, can strengthen margin resilience and customer retention.
- For investors, attention should focus on companies with credible sustainability roadmaps, visible capacity transition plans, and exposure to higher-growth application segments such as automotive electrification, electronics miniaturization, and medical devices. Assessing feedstock flexibility, regional supply positioning, and ESG verification readiness can help identify businesses positioned for durable value creation.
- For procurement and sourcing leaders, diversifying supplier bases, developing scenario-based contracting, and incorporating sustainability criteria into supplier selection can reduce exposure to regional disruptions and price volatility. Establishing clear performance and compliance requirements, while maintaining flexibility for capacity transition periods, will support supply continuity and cost control.
Detailed segmentation data, capacity flow analysis, pricing trajectory modeling, and company-level assessments can provide the precision needed to convert these strategic directions into execution plans. Organizations seeking to deepen their market intelligence and align decisions with granular demand, supply, and competitive signals will benefit from comprehensive research that maps the full landscape and isolates actionable opportunities.
For detailed analysis of this topic, please visit the official page: Methyl Methacrylate (MMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cat Litter Market 2026: Why 5.5% CAGR and Clay Dominance Signal a Strategic Shift
By PW Consulting, 2026-09-21
Strategic Shifts Defining the Global Cat Litter Market (2025–2032)
The global cat litter market has evolved from a low-differentiation commodity category into a strategically contested space shaped by material science, consumer expectations, and tightening operational standards. With the market reaching an estimated USD 11.81 billion in 2025 and expanding at a compound annual growth rate of approximately 5.5 percent through 2032, the category’s trajectory reflects broader shifts in pet care, sustainability, and retail consolidation. Growth is not uniform, and the value creation path is increasingly segmented by formulation performance, supply chain resilience, and brand trust. For executives and investors, the opportunity lies less in chasing volume and more in aligning product portfolios, manufacturing capabilities, and distribution strategies with structural demand changes.
Several factors sharpen the strategic stakes. Household penetration of cats continues to rise in mature markets, while emerging markets are building foundational pet care consumption patterns. At the same time, raw material dynamics, formulation innovation, and regulatory scrutiny of manufacturing hygiene are reshaping competitive benchmarks. The sector’s concentration, with a small group of players holding the majority of industry revenue, suggests that scale, distribution relationships, and brand equity remain powerful moats. Yet the appearance of rapid product experimentation, especially around biodegradable and silica-based formats, indicates that incumbents cannot rely solely on legacy formulations or traditional retail placements.
Three friction points define the current transition. First, raw material price volatility and supply geography create margin exposure for both traditional clay-based and silica-based lines, forcing manufacturers to balance cost control with performance consistency. Second, consumer preference is bifurcating: one segment prioritizes low-cost, high-clumping mineral products, while another increasingly demands natural, low-dust, or flush-friendly alternatives. Third, operational integrity is becoming a strategic differentiator after a high-profile contamination incident involving a widely distributed litter brand, which triggered regulatory review and heightened retailer vigilance. These dynamics do not merely create risk; they establish the criteria by which leading players will be judged over the next several years.
Key Demand and Supply Drivers Reshaping the Category
Technological and formulation innovation is shifting from incremental improvements toward targeted performance solutions. The most notable advances cluster around rapid clumping, odor neutralization, low-dust engineering, and compatibility with automated cleaning systems. Recent product introductions have emphasized fast absorption, instant clumping behavior, and suitability for self-cleaning litter boxes, signaling that convenience is becoming a performance specification rather than a marketing phrase. Alongside this, odor-control strategies are incorporating activated carbon and mineral blends that address the household cleanliness expectations of urban consumers and multi-pet households. The practical implication is that product leadership increasingly depends on formulation precision and repeatability rather than on broad distribution alone.
Worldwide Prescription Cat Food Market
Regulatory and quality standards are also exerting a more direct influence on market behavior. Following a voluntary recall tied to rodent and avian contamination and insanitary storage conditions affecting Tidy Cats products distributed by Gold Star Distribution, Inc., the FDA elevated the recall classification for certain pet products to Class II after reviewing contamination hazards. This sequence matters beyond the immediate compliance event. It demonstrates that hygiene, traceability, and storage controls are becoming procurement concerns for retailers and distributors, especially in markets where consumer trust can shift quickly after a publicized safety issue. For manufacturers, the strategic response is not simply to meet baseline requirements but to embed operational hygiene into product handling, packaging integrity, and distribution protocols as a visible competitive attribute.
Demand-side behavior is changing through a combination of premiumization and value sensitivity. Cat owners are not a monolithic group: some remain highly price-conscious and gravitate toward familiar mineral-based options, while others willingly pay for natural, plant-based, or starch-derived formulations that align with environmental expectations and low-dust preferences. This split is reinforced by the growth of subscription and direct-to-consumer models in certain regions, which reward consistency, packaging convenience, and reliable replenishment. The result is a market where brand trust and usage experience can justify premium positioning even as mainstream segments continue to compete on cost-per-use and retail availability.
Worldwide Natural Cat Litter Products Market
Supply chain and cost structure dynamics add another layer of complexity. Clay remains the dominant raw material base, which means pricing exposure is tied to extraction, processing, freight, and energy costs. Silica-based options face different economics, including synthesis and material intensity considerations. At the same time, natural and biodegradable inputs depend on agricultural and processing supply chains that can vary in consistency, seasonality, and regional availability. Companies that can manage formulation flexibility, lock in dependable sourcing, and minimize waste in conversion processes are better positioned to protect margins through cycles of input inflation. For buyers and distributors, this reinforces the importance of supplier diversification and specification clarity when evaluating long-term contracts.
Competitive Positioning and the Emerging Landscape
The competitive field is anchored by a concentrated group of manufacturers with strong mineral-based capabilities and well-known retail brands, alongside a widening set of regional and formulation-focused producers. TOLSA SA and Laviosa Chimica Mineraria SpA represent established bentonite and mineral-based production profiles with international reach. Oil DRI Corporation of America specializes in absorbent material formulations, while InterSand operates as a North American bentonite and cat litter producer and exporter. On the branded side, The Clorox Company and its Fresh Step portfolio maintain broad retail distribution, and Dr. Elsey's competes in the premium clumping and natural segments. These players benefit from scale, shelf relationships, and formulation familiarity, but their strategic challenge is to sustain relevance as product experimentation and retail assortment complexity increase.
A parallel competitive track is emerging around natural, biodegradable, and plant-based options. Brands such as Naturally Fresh, World's Best Cat Litter, and Kent Corporation illustrate the positioning of pine and plant-based formulations, while manufacturers like Shandong Aiyu Pet Products, Changzhou Sanmei Pet Products, and Anhui Hengjie Group reflect a broader Asian production base spanning cassava, tofu, zeolite, and mixed formats. Several of these companies have expanded visibility through trade activity and product catalog updates. For example, recent exhibition presentations highlighted pure tofu cat litter with natural soybean residue, strong clumping, odor locking with activated carbon, and low dust, while other launches emphasized rapid absorption, instant clumping, and suitability for automatic litter boxes. This activity signals that Asia-based producers are not only competing on cost but increasingly on specification performance and OEM customization capability.
The strategic differentiation among leaders is becoming less about category ownership and more about segmentation mastery. Incumbents with strong mineral-based positions can defend share through consistent performance, packaging innovation, and retail execution. Premium natural brands can build loyalty through perceived safety, environmental alignment, and user experience. Meanwhile, OEM-oriented manufacturers with flexible formulation capabilities can serve private-label programs, regional distributors, and product-development partners seeking to move quickly into biodegradable or mixed-material formats. This creates a landscape where M&A, joint supply arrangements, and brand acquisitions are plausible tools for players seeking to fill portfolio gaps or enter new geographic channels.
Market structure is likely to evolve through both consolidation and fragmentation. Consolidation may occur as larger consumer goods and distribution players acquire regional brands or integrate upstream sourcing to secure input stability. Fragmentation may continue as new entrants target specialized needs, including low-dust formulations, flush-compatible options, and automatic litter box compatibility. The Company is also likely to see increased importance of brand trust and retail compliance, especially after recent contamination-related scrutiny. In practice, this means that competitive advantage will be determined by a combination of formulation consistency, operational discipline, distribution access, and the ability to communicate product benefits in ways that resonate with increasingly discerning buyers.
PW Consulting
Forward-Looking Trends and Commercial Implications
One of the most important forward-looking trends is the growing role of performance-specific formulations in product selection. Not all litter is evaluated primarily on price anymore; automatic cleaning devices, odor sensitivity, dust exposure, and tracking behavior increasingly influence purchase decisions. Over the next three to five years, this should drive further refinement in clumping speed, absorption capacity, and low-dust manufacturing controls. The commercial implication is that product specifications will become more consequential in procurement decisions, and successful players will need to validate performance claims with repeatable production quality rather than relying on broad category messaging.
A second trend is the continued expansion of natural and biodegradable alternatives as a meaningful, though still minority, share of activity. As plant-based, starch-based, and tofu-derived options gain visibility, the strategic question is not whether they will replace conventional mineral products, but where they will hold strongest appeal and how they can be produced consistently at scale. Distribution will matter as much as formulation, because eco-oriented products often require clearer consumer education, distinct shelf positioning, and reliable replenishment cycles. Companies that can stabilize input supply, maintain clumping and odor-control performance, and communicate environmental benefits without sacrificing usability are likely to capture the most durable demand within this segment.
A third trend concerns supply chain integrity and regulatory responsiveness becoming more visible in brand credibility. The recent recall and subsequent FDA classification update have reinforced that hygiene, storage, and distribution conditions are not back-office concerns; they are customer-facing trust signals. Over the coming years, this is likely to translate into tighter audit expectations, stronger quality assurance requirements from retailers, and greater emphasis on traceability in sourcing and logistics. The upside is that disciplined operators can use compliance and safety assurances as differentiators, especially in markets where consumers and retailers are especially sensitive to product cleanliness and brand reliability.
These trends carry both opportunity and uncertainty. On the opportunity side, there is room for manufacturers to capture value through formulation leadership, private-label partnerships, premiumization, and regional expansion into channels that reward consistency and freshness of product design. There is also scope for investors to identify companies with defensible sourcing, scalable OEM capabilities, or brands positioned in high-trust segments. On the risk side, raw material volatility, consumer skepticism after safety incidents, and fragmentation of retail channels could pressure margins and slow share shifts. Demand may also evolve unevenly across regions, meaning that growth assumptions need to be tested against local pet ownership patterns, retail structure, and price sensitivity.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align formulation roadmaps with the ways consumers now evaluate performance. This means investing in clumping reliability, odor control, dust reduction, and compatibility with automated litter systems, while also building supply flexibility across mineral, silica, and natural inputs. Equally important is operational hygiene and traceability, which should be treated as brand assets rather than minimum compliance steps. Companies that can combine specification leadership with dependable production quality will be better positioned to defend premium pricing and secure retailer confidence.
For investors, the most useful discipline is to evaluate competitive positions through the lens of margin resilience and channel access rather than headline category growth alone. Opportunities are likely strongest where companies demonstrate scalable sourcing, formulation versatility, or brand strength in premium or eco-oriented segments. At the same time, diligence should account for input exposure, regulatory sensitivity, and the risk that safety incidents can quickly alter retail placement and consumer trust. Portfolio selection should favor operators that can sustain product consistency and adapt to shifting material economics.
For procurement and distribution leaders, the strategic focus should be on supplier qualification, specification clarity, and contingency planning. Diversifying across mineral and natural-based sources can reduce exposure to single-material volatility, while explicit performance requirements can reduce the risk of assortment inconsistencies. Given the elevated attention to storage and contamination risks, procurement teams should also strengthen audit expectations and handling standards across the distribution chain. In practice, this means treating litter procurement as a quality and reliability decision as much as a cost decision.
For decision-makers seeking to move from directional insight to actionable planning, the market’s segmentation details, regional demand patterns, formulation economics, and competitive moves warrant closer examination. Many of the richest strategic choices—whether in product development, channel expansion, supplier selection, or capital allocation—depend on granular data that cannot be fully captured in a high-level review. Access to a more detailed market study can help translate these trends into specific scenarios, segment-level demand estimates, and tailored recommendations aligned with each organization’s position.
For detailed analysis of this topic, please visit the official page: Cat Litter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Varicella Attenuated Live Vaccine Market: Why 5.65% CAGR Reshapes Immunization Strategies
By PW Consulting, 2026-09-21
Navigating the Varicella Attenuated Live Vaccine Market: Strategic Trends and Commercial Opportunities Through 2032
The global landscape for varicella attenuated live vaccines is entering a period of structured evolution. After years of steady growth driven by routine immunization mandates and catch-up campaigns, the market is now shaped by a combination of regulatory adjustments, supply chain recalibrations, and the gradual entry of differentiated product profiles. Total market revenue has expanded from approximately $145.3 million in 2020 to an estimated $188.5 million in 2025, with a projected compound annual growth rate of 5.65 percent through 2032. By the end of the forecast period, revenue is expected to approach the $275 million threshold. These figures reflect more than simple volume expansion; they signal a market that is maturing in its geographic reach, refining its application mix, and responding to policy shifts that alter how, when, and for whom vaccines are administered.
For executives and strategic planners, the key takeaway is that growth is no longer uniform. Regional maturation patterns, formulation preferences, and target-age expansions are creating pockets of opportunity that reward early positioning and precise commercial execution. At the same time, concentration among leading manufacturers, evolving dosing recommendations, and intermittent supply disruptions introduce execution risk that must be managed proactively.
Market Snapshot: Size, Trajectory, and Structural Realities
The revenue trajectory from 2020 through 2025 demonstrates a market that has absorbed pandemic-era disruptions and returned to a consistent upward path. The acceleration observed between 2022 and 2025 aligns with the normalization of immunization schedules, continued public funding for childhood programs, and incremental expansion of coverage in emerging economies. Looking ahead, the forecast suggests that annual revenue will surpass $240 million in the late 2020s and continue climbing toward $274.9 million by 2032. This pace indicates a market that is not merely repeating historical patterns but is being reshaped by regional policy adoption, age-group expansion, and formulation competition.
The market remains moderately concentrated, with the top three firms accounting for a significant share of revenue and the top five firms capturing an even larger portion. Such concentration provides scale advantages in manufacturing, regulatory navigation, and tendering, but it also compresses the window for late entrants unless they bring clear differentiation in strain profile, dosing convenience, or regional access. The structural reality is that scale and regulatory familiarity still matter, yet the distribution of growth is widening enough to reward players who can align product attributes with specific country-level priorities.
Key Challenges and Inflection Points
Three interconnected challenges define the current juncture and will influence commercial decision-making over the next several years.
First, regulatory guidance on dosing and combination vaccines is shifting practice patterns. Updated immunization schedules have begun to recommend standalone varicella vaccination for toddlers through early childhood in certain settings, responding to safety considerations associated with combined measles-mumps-rubella-varicella formulations. This guidance alters demand dynamics by reinforcing the role of monovalent attenuated live products in routine schedules and by creating a preference environment that favors vaccines with clearly documented safety profiles and flexible administration routes. For manufacturers, this means that clinical communication, dosing instructions, and real-world evidence become more commercially relevant than in prior years.
Second, supply reliability has emerged as a competitive differentiator. Periodic shortages in specific markets have constrained availability to public programs and government procurement channels, underscoring how manufacturing continuity directly affects market share and program trust. When a product experiences availability gaps, procurement teams and public health authorities reassess sourcing options, sometimes accelerating the evaluation of alternative suppliers or regional manufacturing assets. In this environment, supply chain resilience is not an operational nicety; it is a commercial moat.
Third, the market is navigating a transition in target populations and administration pathways. While routine childhood immunization remains the dominant application, growth is increasingly linked to catch-up initiatives and the gradual consideration of adolescent and adult vaccination in specific regions. Concurrently, product labels and monographs are incorporating updated administration instructions, including options for intramuscular or subcutaneous delivery depending on the market and formulation. These shifts broaden the commercial aperture but also require manufacturers to align clinical messaging, training, and pricing strategies with evolving use cases.
Key Drivers Shaping Market Direction
The forward trajectory of the varicella attenuated live vaccine market is being pulled by a set of complementary forces. Understanding how these drivers interact helps explain why growth is concentrating in certain regions, why formulation preferences matter, and why execution quality increasingly separates leaders from followers.
Technological Innovation and Product Differentiation
Product differentiation is moving beyond brand heritage to include strain selection, cell-line platforms, and administration flexibility. Second-generation attenuated live vaccines built on alternative strains and cell substrates are expanding the field, offering manufacturers new ways to position safety, immunogenicity, and supply adaptability. The availability of products leveraging Vero cell-derived platforms and distinct Oka-lineage or MAV/06-type strains demonstrates that differentiation is increasingly technical and regional. Where a given strain or platform aligns with local regulatory expectations and procurement preferences, it can unlock access even in markets where incumbents have long operated.
Administration flexibility is another subtle but meaningful driver. Updated monographs that clarify dosing and route options for specific products reduce friction in clinical settings and supports adoption by providers who value clear, consistent instructions. In practice, this can influence formulary inclusion, training requirements, and procurement decisions, especially where public programs demand predictable administration protocols.
Policy and Regulatory Environment
Policy signals are actively reshaping demand. Adjustments to national immunization schedules, including recommendations that favor standalone varicella vaccination for younger age groups, reinforce the relevance of monovalent attenuated live vaccines and incentivize manufacturers to maintain strong safety communications and real-world data packages. Regulatory authorizations in new countries also matter because they open revenue streams that were previously inaccessible, particularly when paired with public funding or tender eligibility.
Authorization momentum across multiple regions indicates that the regulatory bar, while rigorous, is navigable when manufacturers present robust clinical and quality documentation. As marketing authorizations accumulate in Latin America and Southeast Asia, and as existing products maintain or extend their labels in established markets, the regulatory environment is functioning as both a gatekeeper and a growth catalyst. For companies, the strategic implication is to treat regulatory engagement as a continuous commercial function rather than a one-time milestone, especially where scheduling changes or reimbursement updates can rapidly alter uptake.
Demand-Side Behavior and Public Program Dynamics
Demand is increasingly influenced by public program design and procurement behavior. Routine childhood immunization continues to anchor volume, but catch-up campaigns and targeted initiatives create episodic surges that can shift short-term ordering patterns and strain supply if not anticipated. In parallel, reimbursement frameworks and price lists for public immunization programs provide transparency that shapes contracting and budgeting. When price visibility is high, procurement teams can compare alternatives more efficiently, which increases the importance of competitive positioning on price, availability, and documented service reliability.
A further demand-side shift is the gradual broadening of age focus. Although the core application remains early childhood, interest in adolescent and adult vaccination is emerging in specific markets, often tied to outbreak response, school entry requirements, or employer health programs. This expansion does not replace the childhood base, but it adds a layer of opportunity for products that can demonstrate appropriate safety, dosing practicality, and acceptability in older populations.
Supply Chain and Cost Structure Considerations
Cost structures in this market are influenced by manufacturing complexity, strain maintenance, quality control, and logistics for temperature-sensitive biologics. Regions with established manufacturing hubs and mature cold-chain infrastructure tend to experience lower friction in distribution, while markets dependent on imports can face higher variability in availability and pricing. Recent episodes of localized shortages have highlighted how production scheduling, fill-finish capacity, and regional demand forecasting interact to determine whether a product remains continuously available.
The commercial lesson is that cost leadership alone is insufficient if it comes at the expense of reliability. Buyers increasingly weigh total cost of ownership, including the risk of stockouts, the administrative burden of re-procurement, and the programmatic impact of interrupted immunization schedules. Suppliers that can demonstrate consistent output, transparent lead times, and contingency planning gain a tangible advantage in both public tenders and private-sector contracting.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a small group of manufacturers with established varicella programs and distinct geographic strengths. Each leader has built a strategic position around a combination of strain profile, regulatory footprint, and market access relationships, and each is adapting to the same structural shifts in different ways.
Merck & Co., Inc. maintains a central position in the United States and several additional markets with its monovalent attenuated live varicella vaccine, leveraging deep familiarity with public immunization programs and established supply programs. Its strategic value lies in the continuity of availability and the breadth of clinical and program-level experience, which supports formulary stability and procurement confidence. In a market where schedule changes and safety discussions influence preference, that institutional familiarity is a meaningful asset.
GlaxoSmithKline plc operates with a globally recognized Oka-strain product and has been extending its footprint through recent authorizations, including a 2026 marketing authorization in Canada. Its strategy reflects a combination of regulatory expansion and ongoing distribution in established markets such as the UK and Australia. The company also illustrates how supply continuity can become a focal point: localized shortages have affected availability for public programs in certain periods, reinforcing the importance of manufacturing resilience and proactive communication with health authorities. Updated dosing and administration instructions in product monographs further support clinical adoption by clarifying route options and reducing uncertainty at the point of care.
GC Biopharma Corp. represents a notable expansion vector, with second-generation attenuated live vaccines that have secured recent marketing authorizations in Guatemala and Vietnam, alongside continued distribution in South Korea. Its approach highlights the commercial potential of differentiated strain profiles and targeted regional entry, particularly where a product can be positioned as the first of its type in a market or where local regulatory acceptance aligns with a specific platform. First clearances in Latin America and Southeast Asia demonstrate that regional first-mover advantages can be achieved when product differentiation and regulatory readiness converge.
SK Bioscience Co., Ltd. continues to build on its commercially available attenuated live varicella vaccine with ongoing distribution in South Korea and additional markets such as Turkey. Its strategy emphasizes regional presence and steady availability, aligning with the broader pattern in which established regional suppliers benefit from familiarity, logistics proximity, and program relationships. In practice, this positions the company to participate in both routine programs and targeted campaigns where local execution matters.
Sinovac Biotech Ltd. brings a Vero cell-derived attenuated live vaccine with WHO prequalification and a sequence of recent authorizations, including approval in Argentina and regulatory clearance in China for adolescents and adults. The company’s trajectory illustrates how a platform-based approach and international prequalification can support cross-market expansion, especially when paired with real-world safety data and age-group extensions. The strategic importance here is the ability to leverage a globally recognized quality marker and then convert it into country-level access through local authorizations and program engagement.
Strategic Positioning and Differentiation
Across these leaders, several differentiating levers are visible.
- Regulatory breadth and continuity: manufacturers that maintain active authorization portfolios and update labels as schedules change are better positioned to remain eligible in public programs.
- Strain and platform differentiation: alternative strains and cell-line platforms provide distinct value propositions that can be matched to regional regulatory expectations and safety discussions.
- Supply reliability and program trust: consistent availability and transparent communication reduce the risk of substitution and strengthen long-term procurement relationships.
- Administration flexibility and clinical clarity: clear instructions on route and dosing support provider adoption and reduce implementation friction.
- Real-world evidence and safety communication: documented post-marketing data and proactive safety messaging strengthen confidence in environments where combination vaccine debates influence preference.
The market is not simply consolidating around incumbents; it is fragmenting by region and application while still rewarding scale where it translates into reliability and access. New entrants and regional champions can gain traction by aligning product attributes with specific policy environments and by securing initial clearances that establish a foothold for broader distribution. At the same time, the presence of multiple differentiated products means that competition is increasingly about fit—how well a product matches a country’s schedule, procurement model, and clinical preferences—rather than about brand alone.
PW Consulting Health Care Research Center
Forward Outlook: Trends and Commercial Implications for 2026–2032
Several trends are likely to define the next several years and create the practical opportunities that decision-makers should monitor.
First, regulatory scheduling shifts will continue to influence product mix and demand patterns. As standalone varicella vaccination gains clearer emphasis in certain age groups, monovalent attenuated live vaccines with strong safety documentation and flexible administration options will remain central to routine programs. The commercial implication is that manufacturers should invest in clinical communication and real-world evidence that support preferred placement in schedules, while procurement teams should anticipate how scheduling updates affect ordering cycles and supply planning.
Second, regional authorization momentum will keep opening incremental revenue pools. Recent clearances in Latin America and Southeast Asia show that country-by-country expansion can compound over time, especially when a product is the first of its kind in a market or when it addresses a specific local preference. The opportunity for manufacturers and investors is to identify sequences of authorizations that create cascading access, where early clearance in one country supports credibility and logistics learning for neighboring markets.
Third, supply resilience will increasingly function as a competitive differentiator. Markets that have experienced shortages are likely to place greater weight on manufacturing continuity, regional production capacity, and transparent supply planning when evaluating suppliers. For providers and public programs, the practical benefit is reduced disruption risk; for manufacturers, the strategic task is to align capacity, forecasting, and contingency mechanisms so that availability becomes a visible and credible advantage.
Worldwide Live Attenuated Varicella Vaccine Market
These trends connect directly to commercial opportunities. Companies that can pair differentiated product attributes with reliable supply and proactive regulatory engagement are well placed to capture share in both routine and catch-up settings. Investors should watch for authorization sequences, pricing transparency in public programs, and the ability of suppliers to maintain continuity during demand surges. Procurement organizations should evaluate not only price but also availability history, administration clarity, and the manufacturer’s capacity to support program-level needs during peak periods.
Potential risks and uncertainties remain. Scheduling guidance can change as safety discussions evolve, which may alter demand tempo for specific formulations. Reimbursement frameworks and price lists can shift contracting dynamics, particularly where transparency increases price sensitivity. Manufacturing and logistics disruptions can create localized shortages that quickly affect program trust and market share. Finally, the entry of additional differentiated products may intensify competition in specific regions, compressing margins unless supported by clear clinical or access advantages. These uncertainties do not undermine the overall growth outlook, but they do elevate the importance of planning for variability rather than assuming a smooth trajectory.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product strategy with the realities of schedule preference, regional authorization, and supply continuity. That means treating regulatory updates and administration instructions as commercial assets, maintaining robust safety communication, and building supply plans that can withstand episodic demand surges from catch-up campaigns. Where a differentiated strain or platform is available, the value is greatest when it is matched to a specific regulatory or procurement context rather than positioned generically. Establishing early clearances in targeted markets can create a platform for broader regional expansion, especially when paired with clear clinical messaging and dependable distribution.
For investors, the most informative signals are authorization sequences, supply reliability records, and the alignment of product attributes with emerging schedule and age-group dynamics. Growth is likely to be uneven across regions, so the opportunity set is less about overall market expansion and more about identifying where differentiation, access, and execution converge. Monitoring public price transparency, tender outcomes, and regional shortage episodes can provide early indications of competitive shifts. It is also prudent to assess whether a company’s manufacturing base and contingency planning are sufficient to support continuity if demand patterns change abruptly.
For procurement organizations and program planners, the decision framework should incorporate total value rather than headline price alone. Availability history, administration clarity, and the manufacturer’s ability to support public programs during peak periods can materially affect programmatic outcomes. As schedules and reimbursement details evolve, maintaining a flexible sourcing strategy and sufficient visibility into contract pricing can help prevent disruption. Where possible, evaluating alternatives before a shortage occurs preserves optionality and reduces the operational cost of reactive procurement.
Timely access to detailed, segment-level intelligence matters because the variables that shape outcomes—authorization timing, regional price dynamics, supply continuity, and schedule-driven demand shifts—can change faster than broad market headlines suggest. A focused view of country-level opportunities, product-specific positioning, and supplier reliability patterns supports more confident decisions on capacity planning, market entry, contracting, and portfolio prioritization. For teams that need granular segmentation, competitive benchmarks, and tailored scenario analysis, the full research report provides the structured detail required to translate these trends into concrete action plans.
BCG Vaccine Market
For detailed analysis of this topic, please visit the official page: Varicella Attenuated Live Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roadmarking Paints Market 5.8% CAGR: Strategic Shifts Behind the $10.6B 2032 Trajectory
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Roadmarking Paints Market
The global roadmarking paints market has entered a phase of mature expansion, characterized by steady demand recovery across infrastructure sectors and a gradual shift in material preferences. With a market valuation of 7.18 billion USD in 2025, the sector has demonstrated consistent revenue growth from 5.52 billion USD in 2020, reflecting a compound annual growth rate of 5.8 percent through the forecast period extending to 2032. This trajectory suggests that the industry is moving beyond post-pandemic normalization into a structure defined by regulatory evolution, material innovation, and geographic demand divergence. At first glance, the numbers indicate a reliable growth engine for coatings and infrastructure suppliers. A closer look reveals a market navigating cost volatility, tightening environmental specifications, and intensifying competition among established players and emerging regional suppliers.
The current landscape is shaped by three interconnected dynamics that decision-makers cannot afford to overlook. First, the transition toward low-emission and waterborne coating systems is accelerating, but the pace of adoption remains uneven across regions and project types. Second, raw material price fluctuations, particularly in thermoplastic compounds, specialty resins, and optical glass components, are compressing margins and forcing procurement strategies to become more flexible. Third, infrastructure spending is increasingly being directed toward high-visibility, safety-critical applications, which elevates the standard for durability and reflectivity but also raises the bar for supplier qualification. These forces create a market that is expanding in aggregate yet becoming more selective in how value is captured.
Navigating the Current Inflection Points
The market’s growth narrative is not uniform. While overall demand continues to climb, several structural pressures are reshaping how manufacturers, contractors, and public agencies evaluate roadmarking solutions. The expansion of urban and interurban road networks, combined with periodic resurfacing programs, sustains baseline demand. However, the composition of that demand is shifting. Projects are increasingly scrutinized for lifecycle cost, environmental footprint, and compliance with updated technical specifications. This means that suppliers offering conventional solvent-based products without clear pathways to compliant alternatives face growing friction in specification lists and bidding processes.
At the same time, the industry is witnessing a quiet recalibration of cost expectations. Budget-constrained infrastructure programs are more sensitive to upfront material pricing, which can slow the uptake of premium thermoplastic and specialized cold plastic systems. The tension between performance requirements and cost containment is not simply a procurement inconvenience; it is a strategic variable that determines which product categories gain traction in different project environments. Suppliers that can balance performance, compliance, and total cost of ownership are positioned to secure more consistent wins, while those locked into single-format portfolios may encounter narrowing windows of opportunity.
A third inflection point lies in the standardization and enforcement of roadmarking specifications. Updated technical benchmarks for ready-mixed paints and related marking materials are raising the minimum threshold for adhesion, durability, and reflectivity. These updates are not merely administrative; they influence which formulations are acceptable for public works, how frequently markings must be renewed, and what documentation suppliers must provide. For companies operating across multiple markets, alignment with evolving specifications is becoming a competitive differentiator rather than a baseline requirement.
Key Drivers Reshaping Market Dynamics
Technological Innovation and Material Evolution
Material science is quietly redefining what roadmarking paints can do. Waterborne formulations have advanced significantly in terms of drying time, abrasion resistance, and wet-edge performance, making them increasingly viable for high-traffic corridors where downtime is costly. At the same time, thermoplastic and cold plastic systems continue to be valued for their durability and reflective performance in demanding applications, but their deployment is increasingly tied to project economics and supply availability. The practical outcome is a market where performance claims must be substantiated by application-specific evidence, not just laboratory benchmarks.
Innovation is also extending beyond the paint itself. Improvements in optical glass quality, bead shape consistency, and bond strength are influencing the longevity of marked lines, which in turn affects maintenance cycles and total project cost. Suppliers that integrate material formulation with application technology, including spray equipment compatibility and line-width precision, are delivering more predictable outcomes for contractors and road authorities. This convergence of formulation and application engineering is reducing variability in the field, which is increasingly important as agencies compare bids on the basis of lifecycle performance rather than unit price alone.
Policy and Regulatory Pressures
Regulatory expectations are becoming a central force in product selection. Concerns over volatile organic compound emissions and broader environmental impact are prompting many procurement entities to favor lower-emission alternatives. This does not automatically eliminate solvent-based systems from the market, but it does raise the importance of documentation, emission profiles, and regional compliance pathways. In practice, regulation is acting as both a constraint and a catalyst: it limits the unconstrained use of older chemistries while creating demand for suppliers who can demonstrate credible low-emission performance without sacrificing durability.
Technical specifications are also evolving. Updated standards for ready-mixed road marking paints and related systems are tightening expectations around consistency, application conditions, and performance verification. For manufacturers, this means that product development cycles must account for specification alignment in key markets. For distributors and contractors, it means that stocking decisions and bidding strategies need to reflect the likely direction of regulatory enforcement. The companies that treat specification updates as early signals rather than late obstacles are better positioned to maintain preferred status on project shortlists.
Demand-Side Shifts in Infrastructure and User Behavior
Demand is being influenced by more than road construction volume. Public safety priorities, traffic growth, and the operational needs of airports and commercial parking facilities are all contributing to more frequent marking cycles and higher visibility requirements. Roads and highways remain the dominant application context, but the strategic importance of parking areas and airport tarmacs should not be underestimated. These environments often require specialized markings that can withstand different stress factors, from heavy vehicle turning loads to aircraft pavement conditions, and they tend to be less price-sensitive when reliability is at stake.
There is also a behavioral shift on the part of procurement teams. Buyers are increasingly comparing solutions on a total-cost basis that includes application efficiency, drying time, weather tolerance, and expected service life. This is changing the conversation from “which paint is cheapest per liter” to “which system delivers the best outcome over the project cycle.” Suppliers that can articulate these trade-offs clearly, and back them with field-relevant performance data, are gaining influence in specification decisions.
Supply Chain and Cost Structure Realignment
Cost structures in the roadmarking paints market are under pressure from multiple directions. Volatility in raw material pricing, especially for thermoplastic compounds and specialty glass components, creates uncertainty for both manufacturers and buyers. The challenge is compounded by differences in sourcing availability across resin suppliers and regional supply networks, which can affect lead times and price consistency. For companies relying on fixed-price contracts or tight bidding windows, this volatility can quickly translate into margin compression or project risk.
In response, supply chain resilience is becoming a strategic priority. Some suppliers are diversifying input sources, renegotiating terms with material partners, or adjusting product portfolios to reduce exposure to the most volatile components. Others are investing in formulation efficiency to stretch high-cost inputs while maintaining performance. The broader implication is that cost advantage in this market is increasingly determined by procurement agility and formulation discipline, not simply by scale. Firms that can manage input variability while preserving product consistency will be better equipped to offer stable pricing and reliable fulfillment, which are increasingly valued in competitive procurement environments.
Competitive Landscape and Strategic Positioning
The market is characterized by a concentrated core of established coatings and infrastructure material providers alongside a broader base of regional and specialized players. This structure creates a competitive environment where scale, product breadth, and technical service capability matter, but so does local specification knowledge and adaptability to regional procurement practices. The presence of major global names reflects the importance of cross-market reach, integrated product portfolios, and the ability to support large infrastructure programs with consistent supply and technical documentation.
Several leading companies illustrate the different ways to compete. PPG Industries has built recognition around waterborne and solvent-based traffic paint systems, emphasizing formulation families designed for road marking applications. Its positioning reflects a broader strategy of offering choices that align with varying regulatory and performance requirements while maintaining a consistent technical backbone. Swarco, with operations spanning multiple regions, provides a mix of solvent-based, waterborne, and two-component systems, which allows it to match products to project-specific conditions and specification environments. This breadth supports flexibility in bidding and application scenarios.
Meon Ltd has carved out a role focused on line marking paints and cold plastic systems for roads, parking lots, and airports, highlighting the value of serving multiple application contexts with a coherent product set. Axalta Coating Systems contributes a portfolio that includes spirit-soluble and modified alkyd formulations, showing continued relevance for markets where established chemistries still fit within accepted specifications. Cloverdale Paint Inc underscores another competitive angle: regional specification alignment. Its waterborne traffic paint formulations approved for Canadian infrastructure specifications illustrate how regulatory fit and local qualification can be decisive in securing market access.
Differentiation Beyond Product Catalog Breadth
In a market where many players offer overlapping product categories, differentiation is increasingly determined by how well a supplier can reduce risk and uncertainty for the buyer. Technical support, specification readiness, application guidance, and consistent quality control are becoming part of the core value proposition. Companies that can help contractors and public agencies navigate formulation choices, meet updated standards, and manage application conditions are building a defensible position that is harder to replicate than price alone.
This also means that the competitive battleground is shifting from pure product features to service-integrated solutions. Suppliers that combine reliable product performance with practical field support, clear compliance documentation, and predictable supply are better positioned to win repeat business and preferred supplier status. In contrast, competitors that rely primarily on catalog breadth without strong technical and service integration may find themselves vulnerable when buyers compare total project risk and lifecycle outcomes.
Portfolio Evolution and Market Structure Trends
The competitive landscape is likely to continue evolving through a combination of consolidation, portfolio specialization, and selective entry by regional players. Larger firms may pursue broader coverage through acquisitions or geographic expansion, aiming to strengthen supply continuity and specification reach. Smaller and mid-sized suppliers may compete by focusing on niche applications, regional specifications, or specialized material systems that larger players deprioritize. At the same time, new entrants with differentiated formulations or application-focused technologies could gain traction in segments where durability, drying speed, or environmental compliance are especially valued.
One important trend is the growing importance of portfolio coherence. Buyers are less interested in isolated product lines and more interested in suppliers that can address a range of marking needs across roads, parking areas, and airports with consistent quality and clear technical guidance. This favors companies that can offer a structured portfolio rather than fragmented offerings, while still retaining the flexibility to serve project-specific requirements. Another trend is the increasing relevance of regional compliance knowledge. As specifications become more localized and more stringent, suppliers with strong familiarity with local standards and procurement practices are gaining an edge in winning formal qualifications and specification inclusions.
Forward Outlook: Trends Shaping the Next 3 to 5 Years
Over the next several years, the roadmarking paints market is likely to be shaped by three reinforcing trends. The first is the continued migration toward lower-emission and more durable marking systems, driven by regulatory expectations, safety priorities, and total-cost considerations. This will not result in a single dominant chemistry across all contexts. Instead, it will produce a more segmented market in which waterborne, thermoplastic, and cold plastic solutions coexist, each anchored to specific application profiles and specification regimes.
Traffic Marking Paints Market
The second trend is the growing emphasis on supply chain stability and cost predictability. As raw material volatility and specification updates continue to influence procurement decisions, suppliers that can manage input risk, maintain consistent quality, and offer transparent pricing logic will be rewarded with stronger customer relationships and more resilient order flow. This trend favors organizations that treat supply chain management as a strategic capability rather than an operational back-office function.
The third trend is the increasing role of performance verification and lifecycle thinking in specification and bidding processes. Buyers are likely to place greater weight on demonstrated durability, reflectivity retention, application efficiency, and compliance readiness. This creates opportunities for suppliers that can provide credible evidence of field performance and support buyers in evaluating total project outcomes. It also introduces risk for companies that depend on price-based competition without a clear performance narrative or specification alignment.
These trends open commercial opportunities in several areas. Suppliers with strong waterborne or low-emission portfolios can benefit from specification shifts in markets where emission constraints are tightening. Companies with robust thermoplastic and cold plastic capabilities can focus on high-durability applications where performance justifies premium positioning, especially if they can manage cost exposure effectively. There is also room for service-led differentiation, where technical support, application guidance, and specification expertise become the basis for preference rather than product features alone. At the same time, uncertainty remains. Raw material cost swings, uneven regulatory enforcement, and project budget constraints can all slow adoption or shift demand between product categories. Firms that monitor these variables closely and adjust portfolios and procurement strategies accordingly will be better prepared to capture upside while limiting downside.
Strategic Implications for Decision-Makers
For Manufacturers and Material Formulators
Portfolio strategy should be guided by the need to balance compliance, durability, and cost control. Rather than treating product lines as static offerings, manufacturers can benefit from aligning formulations with the specification trajectories of key markets and identifying where performance claims can be credibly extended. Investment in application-relevant testing, clear documentation, and supply chain flexibility can strengthen competitive positioning more reliably than incremental catalog expansion alone. Companies should also consider where they can reduce exposure to volatile inputs without compromising field performance, since cost stability is increasingly part of the value proposition.
PW Consulting
For Investors and Strategic Buyers
The market offers exposure to steady infrastructure-linked demand, but value creation will likely come from companies that can manage regulatory transitions, supply variability, and application performance in an integrated way. Due diligence should pay attention to specification alignment, regional qualification strength, and the ability to serve multiple application environments with coherent product and service offerings. Businesses that rely heavily on single-format dependency or on price competition in volatile input conditions may face narrower margins for error. Strategic acquisitions or partnerships that expand compliance coverage, regional reach, or service capability can create advantages in a market where buyer preferences are shifting toward reliability and lifecycle value.
For Procurement Teams and Infrastructure Buyers
Evaluating roadmarking solutions with a total-cost perspective can reduce project risk and improve long-term outcomes. This means accounting for application speed, drying behavior, weather tolerance, expected service life, and compliance readiness alongside unit pricing. Early engagement with suppliers on specification alignment and performance expectations can help avoid mismatches during bidding and execution. Procurement teams can also benefit from tracking specification updates and material availability trends, since these often signal which product categories will become easier or harder to source at competitive terms in upcoming project cycles.
Paint Market
For all of these audiences, the value of detailed market intelligence lies in its ability to connect broad trends to specific decisions. Segment-level demand patterns, regional specification trajectories, raw material exposure by product category, and competitive positioning by application context all influence how the market will evolve beyond the headline growth narrative. A more granular view helps manufacturers prioritize formulation and portfolio choices, helps investors identify where durable advantage is being built, and helps procurement teams structure sourcing strategies that are resilient to both regulatory and cost-side uncertainty.
The roadmarking paints market is not simply expanding; it is restructuring around performance expectations, environmental mandates, and supply chain realities. Companies that interpret these signals early and align their strategies accordingly are more likely to convert market growth into sustained commercial advantage. For decision-makers seeking a deeper, segment-level view of demand splits, regional specification trends, raw material exposure, and competitive positioning across product types and application contexts, the full PW Consulting market report provides the additional granularity needed to support planning, procurement, and investment decisions with greater confidence.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com